Battery Repair, Refurbishment and Remanufacturing in India 2026: Economics and Compliance
By Sudarshan Karweer · sudarshan@growthifye.com · +91 84510 99371 (Call / WhatsApp) · 2026-08-29
India’s battery circularity market is often discussed through two headline themes: recycling and second-life stationary storage. In practice, a large and fast-forming middle layer sits between first use and material recovery: repair, refurbishment and remanufacturing of battery packs, modules and selected sub-components. For Indian EV fleets, OEM ecosystems, C&I users, financiers and utilities, this layer matters because it directly affects warranty claims, residual value, replacement capex, downtime and EPR planning.
In 2026, this is no longer a niche workshop activity. It is becoming an organised operating model with defined safety protocols, traceability requirements, quality gates and measurable unit economics. For two-wheelers, three-wheelers, LCV fleets, telecom backup systems and behind-the-meter storage assets, a structured refurbishment pathway can defer replacement, recover value from partially degraded assets and reduce avoidable recycling volumes. But it only works where diagnostics, parts availability, approvals, liability allocation and compliance are tightly designed.
This article focuses on a topic distinct from recycling plants and second-life BESS deployment: how battery repair, refurbishment and remanufacturing businesses are being structured in India in 2026, what economics look like, where the safety and policy constraints sit, and what lenders and asset owners should underwrite before scaling.
Why this segment matters in India now
India’s battery installed base has expanded sharply across e-mobility and stationary applications. Two-wheelers and three-wheelers continue to dominate battery volumes by unit count, while buses, LCVs and C&I storage systems contribute larger pack sizes and more consequential replacement decisions. A meaningful share of these assets does not need immediate recycling at first fault event or early capacity fade.
Three market realities are driving refurbishment demand in 2026:
- Fleet operators are under pressure to reduce battery replacement opex and improve vehicle uptime.
- OEMs and distributors want lower warranty settlement costs without compromising safety.
- Financiers are increasingly valuing recoverability and residual value pathways in battery-backed portfolios.
For many use cases, the gap between “fully serviceable” and “end of life” is commercially important. Packs may fail because of BMS issues, connector corrosion, thermal event exposure, enclosure damage, coolant leakage, fuse isolation, busbar failure, water ingress or a limited set of weak modules. In such cases, controlled repair or module-level refurbishment may restore useful life at a fraction of full replacement cost.
Typical economic triggers seen in India in 2026 include:
- Two-wheeler pack replacement cost often ranging from about Rs 35,000 to Rs 75,000 depending on chemistry, capacity and OEM architecture.
- Three-wheeler battery replacement frequently in the Rs 90,000 to Rs 2.5 lakh range.
- LCV and bus packs running into several lakh rupees to well above Rs 20 lakh for large systems.
- Downtime cost for commercial fleets often exceeding direct repair cost if turnaround is slow.
In that context, even a 20% to 40% saving against full replacement can materially change lifecycle economics.
What counts as repair, refurbishment and remanufacturing
These terms are often used loosely, which creates confusion in contracts and compliance.
A practical operating distinction is useful:
- Repair: Limited intervention to restore original function without major rebuild. Examples include BMS replacement, harness repair, fuse or relay replacement, enclosure sealing and software recalibration.
- Refurbishment: Deeper intervention involving testing, replacement of degraded modules or cells within approved limits, rebalancing, enclosure restoration, thermal interface renewal and validated performance testing.
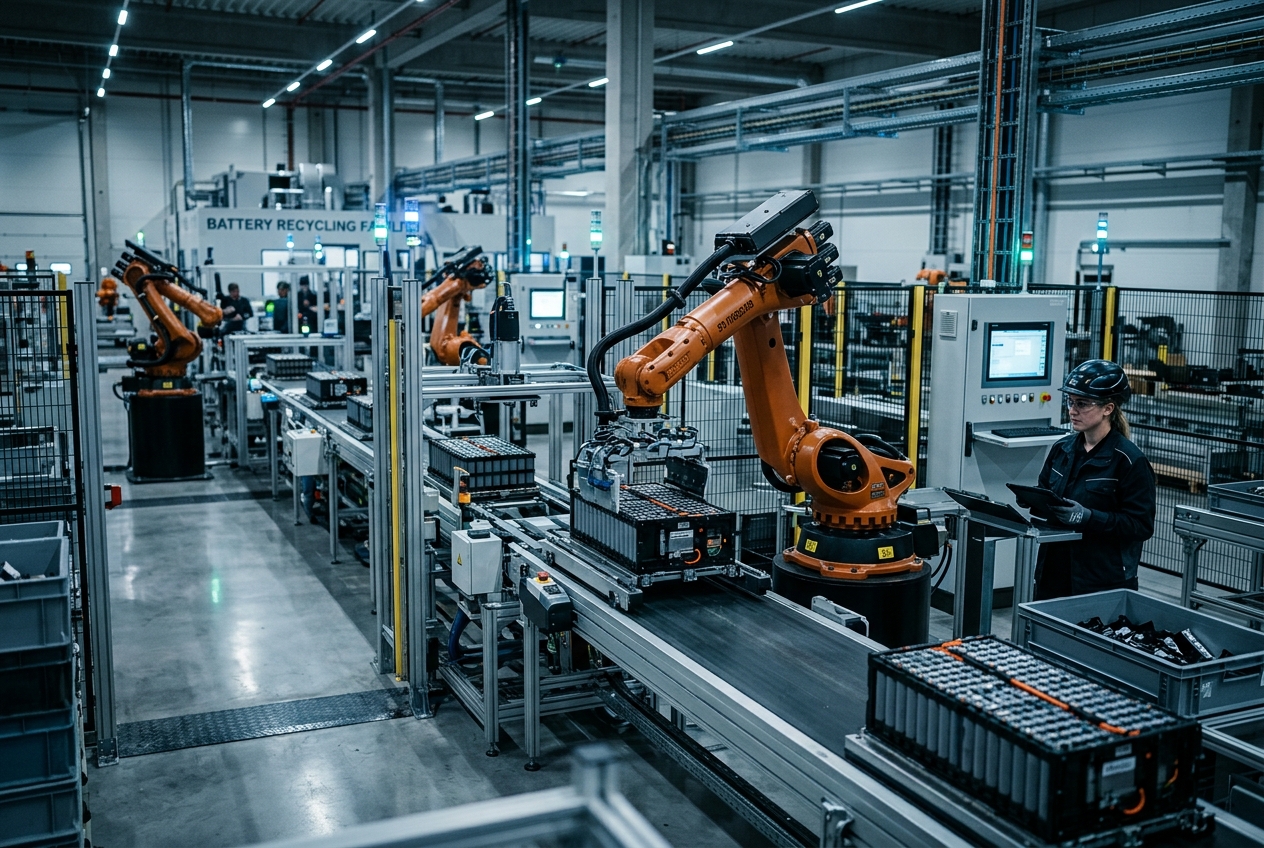
- Remanufacturing: A more industrial process where returned batteries are disassembled, inspected, rebuilt with qualified components, retested to a defined specification and reissued under a formal quality system.
For asset owners, the distinction matters because warranty, insurance, transport classification, resale value and EPR treatment may differ depending on the intervention depth and who performs it.
In India, the most bankable models in 2026 are those where refurbishment or remanufacturing is done either by the OEM, by an OEM-authorised partner, or by a specialist circularity operator working under tightly defined SOPs and digital traceability.
Unit economics: where value is created and where it leaks
The business case for battery refurbishment is attractive only when diagnosis is accurate, throughput is sufficient and scrap leakage is controlled. The broad cost stack in India typically includes:
- Reverse pickup and compliant transport
- Quarantine, triage and incoming inspection
- Electrical diagnostics and thermal screening
- Disassembly labour and safe workstations
- Replacement parts such as BMS, contactors, connectors, harnesses, seals or modules
- Test cycling and validation
- Packaging, reinstallation and field support
- Documentation, serial traceability and warranty provisioning
- Residual scrap handling and recycling
At a high level, 2026 market observations suggest the following indicative ranges:
- Light EV battery repair involving electronics and minor hardware may cost 8% to 18% of new pack value.
- Module-level refurbishment for small EV packs may land around 25% to 55% of new pack value, depending on module availability and rejection rate.
- Larger fleet packs can show lower percentage repair cost but much higher absolute rupee values.
- Logistics and diagnostic overhead can consume 10% to 25% of total refurbishment cost if network density is weak.
Gross margin is highly sensitive to first-pass diagnosis quality. Misclassification is expensive. A pack that is collected, opened and worked on but later deemed unsafe for refurbishment incurs logistics, labour and compliance cost before it is redirected to recycling. This is why structured Reverse logistics and pre-screening protocols are commercial, not just operational, priorities.
A useful decision rule for owners is the refurbishment ratio:
- If repair or refurbishment cost is below roughly 35% to 45% of replacement cost and expected restored life is above 30% to 50% of a new asset’s remaining economic life, the case is often viable.
- Above 50% to 60% of replacement cost, direct replacement or conversion into a second-life application may become superior, especially where warranty support is weak.
This is not universal. It depends on fleet duty cycle, availability of OEM parts, tariff-linked savings, financing structure and downtime penalties.
Safety, liability and quality control are the real gating factors
The biggest mistake in this segment is to view refurbishment as a low-tech extension of after-sales service. In reality, the safety envelope is narrow. A battery with hidden internal damage, latent thermal risk or compromised insulation can pass superficial checks and still fail later in the field.
That is why serious operators in 2026 are building layered acceptance criteria before any battery enters refurbishment:
- Visual damage screening for swelling, puncture, deformation, corrosion and fluid ingress
- Open-circuit voltage and pack isolation checks
- BMS fault-code extraction and event history review
- Thermal imaging and temperature anomaly detection
- Insulation resistance testing
- Controlled charge-discharge evaluation where safe to do so
- Cell or module grading against defined variance thresholds
Common no-go categories include:
- Confirmed internal short risk
- Severe thermal event history
- Significant crash damage in traction batteries
- Repeated overcharge or deep discharge outside approved limits
- Water ingress affecting core electrochemical integrity
- Unknown origin or broken traceability
For lenders and insurers, the key question is not only whether the battery was repaired, but whether the process followed documented engineering controls and whether post-repair performance can be evidenced. This is where End-of-life fleet audits become valuable upstream. They help segment battery populations into repairable, refurbishable, second-life suitable and direct-recycling candidates instead of sending all returns into one mixed-cost stream.
Policy, compliance and EPR implications in 2026
India’s regulatory architecture around waste batteries and producer responsibility has made traceability and channel discipline more important. While the exact commercial interpretation depends on battery category, ownership structure and transaction design, 2026 market practice increasingly expects clear documentation across collection, diagnosis, repair decision, transfer, residual waste disposal and final recycling.
From a compliance perspective, five issues matter most:
- Producer responsibility and recordkeeping under the battery waste framework
- Movement of damaged or end-of-life batteries through authorised channels
- Worker safety, hazardous material handling and incident response
- Digital trail for serial numbers, chemistry, intervention history and material disposition
- Contractual clarity on whether a refurbished battery re-enters service under OEM warranty, third-party warranty or limited service guarantee
EPR compliance becomes more strategic when refurbishment is scaled. Why? Because extending first-life utility can alter return timing, channel economics and claims planning. It can reduce premature scrap generation, but it also requires disciplined accounting of which units were restored, which parts were replaced, and which residual materials were sent to authorised recyclers. That accounting is no longer optional if an OEM or fleet wants to defend product stewardship and avoid disputes around end-of-life responsibilities.
The practical implication for battery and mobility companies is simple: build refurbishment data architecture alongside operating capability, not after scale-up. Serial-level event logging, chain-of-custody records and disposition codes should be embedded from day one. This is where Growthifye’s capabilities in EPR compliance and Circularity reporting can support management teams and investors who need auditable workflows rather than generic sustainability claims.
Business models that are emerging in India
The Indian market is not converging on one single refurbishment model. Instead, four models are visible in 2026.
The first is the OEM-controlled service loop. This works best where battery design is proprietary, telematics access is strong and spare modules are available. It typically delivers the best safety and warranty confidence, but capacity can become constrained if return volumes rise quickly.
The second is the authorised partner network model. Here, approved service partners perform defined repairs and selected refurbishment activities under OEM SOPs. This can improve turnaround time across multiple states, but only if training, test equipment and audit routines are standardised.
The third is the fleet-captive refurbishment hub. Large e-commerce, delivery, mobility or bus operators with concentrated battery populations may centralise triage and module replacement for approved chemistries. The advantage is lower logistics cost and tighter downtime control. The challenge is liability if process governance is weak.
The fourth is the specialist circularity platform. These operators combine diagnostics, reverse collection, refurbishment, residual recycling and sometimes Second-life battery applications under one commercial umbrella. This model is promising for mixed-brand portfolios but requires strong technical controls and careful boundary setting with OEMs.
For investors, throughput density matters more than workshop count. A small number of well-run regional hubs with strong triage quality can outperform a large but inconsistent service footprint.
How C&I users, utilities and lenders should evaluate opportunities
C&I users and utilities may assume this topic is relevant only to EV fleets. That is too narrow. Battery refurbishment logic increasingly matters for telecom backup systems, behind-the-meter storage, renewable integration pilots, campus microgrids and distributed energy service models.
A procurement or underwriting checklist should include:
- Asset population by chemistry, age, use profile and fault history
- Percentage of failures likely to be electronics versus electrochemical degradation
- Approved intervention levels by OEM or engineering authority
- Turnaround time targets and spare strategy
- Refurbished performance threshold, such as minimum retained capacity and cycle expectation
- Warranty structure and exclusions
- Residual recycling partner and scrap monetisation method
- Incident response protocol and insurance coverage
For lenders, a practical underwriting question is whether refurbishment improves cash flow resilience. If battery failures can be restored at materially lower cost than replacement, DSCR volatility may reduce for fleet operators or storage asset owners. But that upside should only be credited where there is a proven workflow, historical diagnostic data and defined liability backstops.
For utilities and public-sector entities evaluating circular procurement, the opportunity lies in standard-setting. Tenders can specify traceability, testing and end-of-life routing conditions rather than treating all “repaired” batteries as equivalent. That creates market discipline and reduces unsafe informal activity.
What a workable execution strategy looks like
An effective battery refurbishment programme in India in 2026 usually starts with portfolio segmentation rather than infrastructure spend. The right sequence is:
- Audit installed battery base and return streams
- Define acceptance and rejection criteria by chemistry and application
- Map logistics lanes, packaging standards and emergency response needs
- Establish diagnostics protocol and test equipment list
- Lock authorised parts and module sourcing strategy
- Design digital traceability and compliance records
- Contract residual recycling and material recovery channel
- Pilot with one fleet cluster or one product category before wider rollout
The most common failure points are not technological. They are operational and contractual:
- Incomplete fault data from field teams
- Mixed battery populations arriving without traceability
- Lack of approved spare modules
- Poor turnaround discipline causing fleet downtime
- Unclear ownership transfer during refurbishment
- Weak warranty language creating disputes after redeployment
For many sponsors, the best first step is not to build a facility immediately. It is to undertake a detailed return-stream and economics study, followed by SOP design and a pilot throughput plan. That is especially true where the business case depends on multi-state collections or mixed-brand batteries.
India’s circular battery market in 2026 is entering a more granular phase. Recycling remains essential, and second-life deployment will continue to expand. But repair, refurbishment and remanufacturing are where a substantial share of near-term value can be captured, provided safety, compliance and process control are not compromised. For OEMs, fleets, C&I users and lenders, this segment offers a route to lower lifecycle cost and stronger asset productivity. The winners will be those who treat it as an engineered, traceable and financeable operating system rather than an ad hoc service function.
If you are evaluating a refurbishment strategy, return-stream economics or compliant operating model for battery circularity, contact Growthifye’s advisory desk. We support market assessment, operating design, compliance architecture and execution planning across India.
Explore Growthifye's related capabilities
This analysis connects directly to our advisory practice: End-of-life fleet audits · Second-life battery applications · Module & battery recycling · EPR compliance.
About the author

Chief Executive Officer, Growthifye — With over 23 years in management consulting, Sudarshan has taken businesses from concept to scale — building and scaling new-age digital and energy businesses.
- 23+ years in management consulting
- EY alumnus
- Led large-scale BESS programmes, capital raises and advisory mandates
Want this analysis applied to your project?
Talk to our team