CBG Digestate Management in India 2026: Economics, Compliance and Market Design
By Sudarshan Karweer · sudarshan@growthifye.com · +91 84510 99371 (Call / WhatsApp) · 2026-09-14
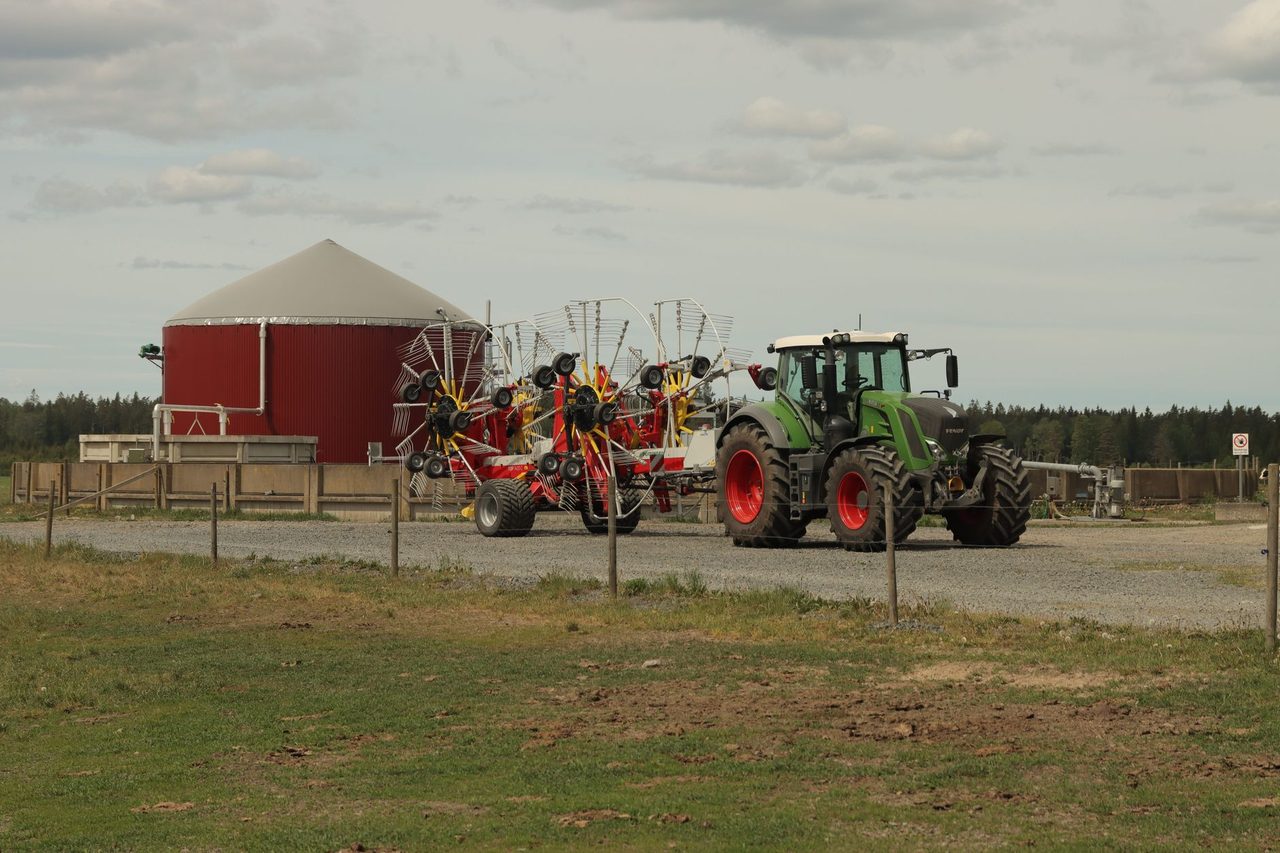
Photo: Efrem Efre on Pexels
# CBG Digestate Management in India 2026: Economics, Compliance and Market Design
India's compressed biogas pipeline is finally being evaluated more rigorously in 2026. Developers, oil marketing companies, lenders and state agencies are no longer satisfied with headline CBG output alone. They want to know whether the project can manage slurry, monetise digestate, stay compliant under fertiliser rules, and avoid environmental non-compliance that can shut a plant or erode debt service coverage.
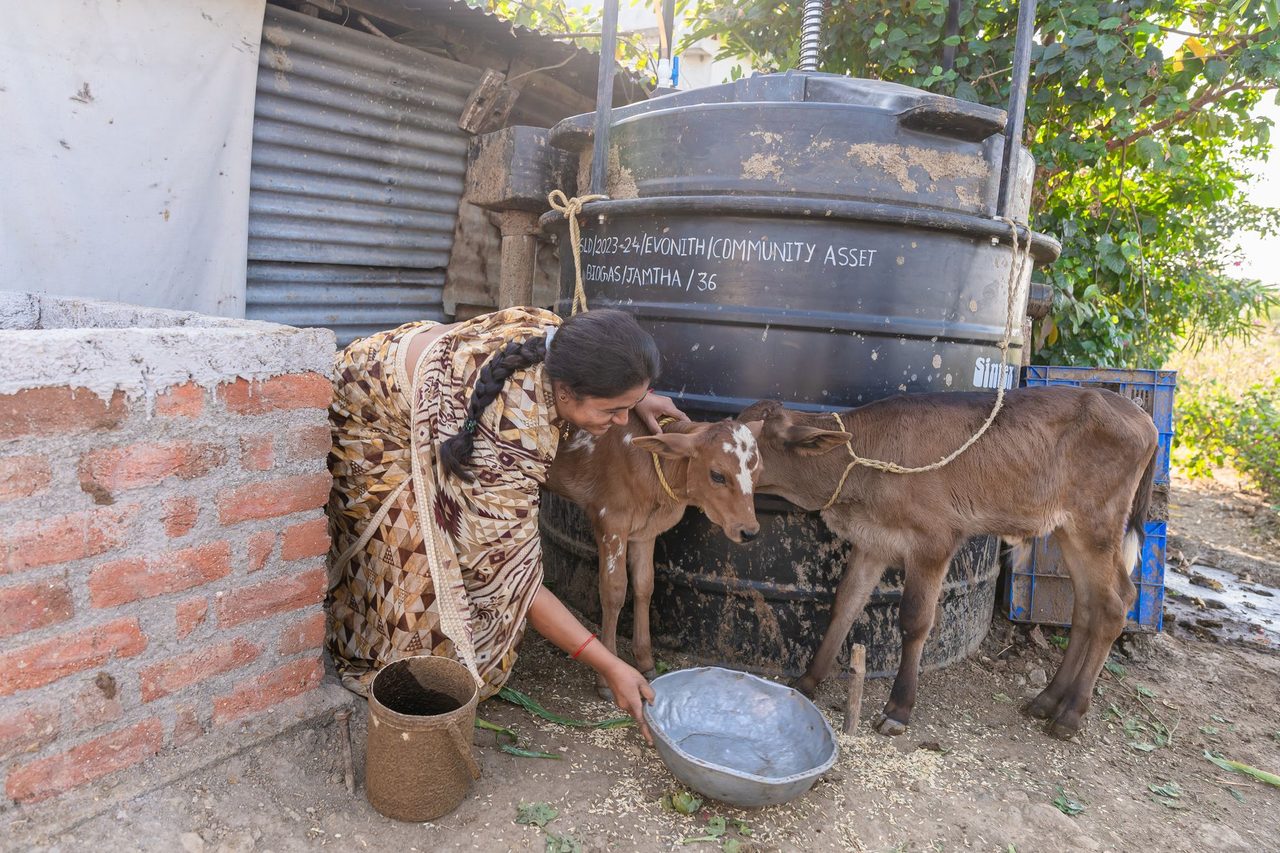
That scrutiny is justified. In many Indian CBG projects, digestate is still treated as an afterthought, even though it can represent 85-95% of mass leaving the digester. For a 10 TPD CBG plant, daily digestate generation can easily exceed 80-120 tonnes depending on feedstock moisture, retention time and solid-liquid separation design. If the evacuation, processing and sale of digestate are weak, the project faces storage overflow, odour complaints, nutrient loss, and rising transport costs. If done properly, digestate becomes a bankable co-product with measurable nutrient value and a role in chemical-fertiliser substitution.
This article focuses on a distinct but under-addressed circularity theme: digestate management as the missing commercial layer in India's CBG scale-up. For C&I buyers, RE developers, lenders, utilities and policymakers, the core question in 2026 is no longer whether digestate has value in theory. The question is whether that value can be captured consistently through process design, compliance, product standardisation and local market creation.
Why digestate now matters to CBG bankability
SATAT-linked CBG development has created momentum, but project underwriting has become tighter. Lenders reviewing 2026-era projects increasingly test five issues beyond biogas yield:
- guaranteed feedstock quality and seasonality
- actual parasitic load and uptime
- gas purification losses and methane slip
- digestate handling and environmental compliance
- contracted offtake for both gas and manure products
A project that assumes digestate disposal is free will often misstate opex. A project that overstates digestate revenue without product registration and channel partners will overstate EBITDA. Both are common errors.
In current Indian market conditions, digestate can influence project cash flow in three ways:
- avoided disposal cost
- direct sales of liquid or solid organic manure
- indirect support to feedstock sourcing through farmer relationships
For mixed agri-residue, press mud, cattle dung and food-waste plants, digestate monetisation may contribute only 5-15% of total revenue, but that share is often the difference between a stressed and a comfortable DSCR, especially where feedstock transport distances exceed 25-40 km.
Developers should remember a simple point: financiers are less interested in theoretical nutrient content than in repeatable evacuation. A lower-price but contracted digestate offtake model is usually more financeable than a high-price merchant assumption with no distribution network.
The 2026 regulatory framework developers cannot ignore
Digestate commercialisation in India sits at the intersection of environmental compliance, fertiliser regulation, state pollution control oversight and local transport/storage rules. In 2026, the most relevant framework for sale as an agricultural input remains the Fertiliser Control Order, 1985, as amended, alongside related standards for city compost, organic fertilisers and bio-stimulant categories where applicable. Developers must also assess how state agriculture departments interpret product categories in practice.
At the project level, the following approvals and compliance tracks tend to matter:
- consent to establish and consent to operate from the State Pollution Control Board
- management plan for effluent, digestate storage, odour and runoff
- FCO-linked registration, labelling and quality testing if sold as fertiliser/manure product
- weights, packaging and traceability requirements for bagged products
- local groundwater and land-application restrictions where digestate is applied directly
A recurring financing problem in 2026 is mismatch between DPR assumptions and actual compliance pathway. Some DPRs assume the digestate can be sold immediately as organic manure, while in reality the developer still needs drying, enrichment, granulation or registration work to sell beyond nearby farms. That delay can last 6-12 months after plant commissioning and should be reflected in working capital planning.
For lenders, the practical diligence questions are straightforward:
- Is digestate being sold as raw slurry, liquid fertiliser, dried manure, composted material or fortified granules?
- Does the plant design match the claimed product route?
- Have product tests been conducted on expected feedstock mix, not just a sample batch?
- Who bears the cost of quality failures or off-spec nutrient content?
- Is there seasonal storage capacity for monsoon and low-demand periods?
Technology choices change economics more than most DPRs admit
Not all digestate is commercially equal. The chosen process route affects moisture, nutrient retention, haulage radius, capex and achievable selling price. In India, most CBG plants in 2026 are evaluating one of four broad digestate strategies.
- direct land application of slurry within a limited radius
- solid-liquid separation with sale of liquid fraction and local handling of solids
- composting/drying of solids into marketable manure
- enrichment or granulation for higher-value branded output
Each route has different economics.
Direct slurry application is the lowest capex option, but generally the weakest for scale because transport economics deteriorate quickly. At 90-95% moisture, moving slurry beyond 10-20 km is rarely efficient unless there is pipeline transfer, contiguous farmland, or captive consumption. For many plants, the delivered nutrient value does not justify the freight.
Solid-liquid separation usually adds screw press or decanter capex, plus pumps, storage lagoons or tanks and handling systems. For a mid-sized 5-10 TPD CBG plant, digestate processing block capex can range from roughly Rs 1.5 crore to Rs 6 crore depending on separation, drying, compost pads, civil works and automation. More advanced drying and granulation lines can push this higher.
However, separation often improves practical monetisation. A stackable solid fraction reduces freight cost per unit nutrient delivered. The liquid fraction can be marketed locally through tanker distribution or fertigation users if quality consistency is proven. In some clusters, developers are also blending digestate with crop-specific nutrient formulations, though this requires tighter quality control and stronger channel partners.
The trap is thermal drying without a market study. Drying can look attractive in a DPR because it improves handling and shelf life, but it raises power or fuel demand materially. If waste heat is unavailable or unreliable, drying economics can weaken quickly. At industrial tariffs of roughly Rs 7-9.5 per kWh in many states in 2026, the energy penalty matters. Developers should model realistic parasitic load and monsoon performance rather than brochure values.
This is where Growthifye's capabilities in Circularity reporting and EPR compliance often intersect with waste-to-energy advisory. Buyers and financiers increasingly ask for mass-balance clarity, nutrient recovery accounting and auditable environmental performance, not just equipment lists.
What digestate is actually worth in Indian markets
The answer depends less on chemistry alone and more on moisture, packaging, local crop patterns, channel economics and trust.
In 2026, indicative ex-plant realisations seen across Indian markets for digestate-derived products vary widely:
- raw slurry: often negligible to Rs 300 per tonne, and in many cases negative if transport is subsidised by the plant
- separated wet solids: roughly Rs 500-1,500 per tonne depending on dryness and local demand
- dried organic manure/compost-like product: around Rs 2,000-5,000 per tonne
- fortified or branded organic input: can exceed Rs 5,000 per tonne, but only with registration, distribution and performance acceptance
These are broad working ranges, not universal prices. In many districts, the practical bottleneck is not willingness to pay but first-mile movement and field demonstration. Farmers compare digestate against urea, DAP, FYM, poultry litter, press mud, city compost and local dealer credit terms. A nutrient-rich product without dealer financing or agronomy support may still fail to move.
For that reason, serious developers are now building district-level go-to-market models. That means mapping:
- dominant crops within 25, 50 and 75 km
- seasonal nutrient application windows
- competing organic inputs and prices
- dealer network margins
- moisture tolerance of target buyers
- bagged versus bulk preference
A bagged product may fetch a better headline price, but bagging, warehousing and channel margin can absorb much of the premium. A bulk institutional sale to sugar mills, plantations, FPOs or contract-farming networks may be less glamorous but often more stable.
One useful rule of thumb for lenders: assume conservative digestate revenue in the base case and test upside separately. If the project still clears minimum coverage thresholds under conservative assumptions, digestate upside becomes a cushion rather than a crutch.
Risk allocation in offtake contracts and project finance
Digestate risk is usually misallocated in project documents. EPC contracts may promise processing capability, but not product marketability. O&M contracts may cover uptime, but not nutrient consistency. Gas offtake agreements rarely solve by-product evacuation. The result is a stranded liability sitting on the SPV balance sheet.
In 2026, stronger projects are addressing digestate via dedicated commercial structures such as:
- annual or multi-season offtake agreements with agri-input distributors
- anchor sales to nearby plantations, sugar ecosystems or large farmer-producer organisations
- toll-processing arrangements where a third party dries or enriches material
- service contracts for transport, field application and dealer development
Key bankability terms include:
- minimum offtake quantity or evacuation commitment
- quality specification and test methodology
- moisture band and rejection protocol
- transport responsibility and delivery point
- payment cycle and inventory risk
- monsoon-period backup storage obligations
Lenders should also check whether land parcel planning is adequate. Digestate yards, curing pads, runoff channels and covered storage are frequently under-dimensioned in Indian CBG layouts. During monsoon, this becomes an operational and compliance problem quickly.
Where project sponsors are integrating advisory support, End-of-life fleet audits and Reverse logistics may sound unrelated to CBG at first glance, but the same circularity discipline applies: map material flows early, assign responsibility contractually, and do not assume downstream evacuation will solve itself after commissioning.
Policy opportunities for states and utilities
If India wants CBG projects to scale beyond demonstration economics, digestate policy needs as much attention as gas pricing. Three policy gaps remain visible in 2026.
First, quality standardisation and farmer confidence remain uneven. States can support district demonstration programs with agriculture universities and KVK networks so digestate products are compared transparently across crops and soil conditions.
Second, logistics support is weak. CBG clusters need co-located storage, composting and distribution infrastructure, especially where multiple small and mid-sized plants operate within one agri-belt. Shared processing parks may lower capex per plant.
Third, municipal and utility procurement frameworks still focus more on waste tipping and gas offtake than nutrient recovery. Urban wet-waste and sewage-linked bioenergy projects should be evaluated on full circular value, including avoided landfill burden and soil-input substitution.
Policymakers should also avoid an overly simplistic assumption that every digestate stream can directly replace chemical fertilisers one-for-one. Agronomic performance depends on nutrient availability, application timing and soil context. The real opportunity is to expand integrated nutrient management, not to market digestate with inflated claims.
A practical checklist for developers and lenders in 2026
Before financial close or final investment decision, CBG stakeholders should test the following:
- Have digestate volumes been estimated from realistic feedstock moisture and retention assumptions?
- Is storage sized for worst-case evacuation delay, including monsoon conditions?
- Does the chosen process route match the target market: slurry, bulk solids, bagged manure or fortified product?
- Are FCO and lab-testing pathways budgeted in capex and pre-operative expenses?
- Has the project mapped crop demand and channel economics within a viable radius?
- Are digestate revenues conservative in the base case model?
- Is there a fallback disposal or captive-use plan if offtake underperforms for one season?
- Are odour, runoff and community-interface risks reflected in O&M planning?
For C&I consumers and industrial groups considering CBG sourcing, digestate discipline is also a procurement issue. A plant that handles by-products poorly is more likely to face operational interruptions, local opposition and compliance notices. Counterparty quality should therefore be assessed across the full waste-to-energy chain, not only at the gas outlet flange.
In 2026, the strongest Indian CBG platforms will be those that treat digestate as a designed product stream rather than a residual burden. The projects most likely to attract affordable capital are not the ones with the highest theoretical manure price in Excel. They are the ones with realistic nutrient economics, credible compliance, adequate storage, and local market pathways that can survive a weak season.
For sponsors, utilities, financiers and policymakers, that is the real circularity test.
If your team is evaluating a CBG, waste-to-energy or broader circularity platform, contact Growthifye's advisory desk for practical support on project structuring, compliance, market design and bankability.
Explore Growthifye's related capabilities
This analysis connects directly to our advisory practice: End-of-life fleet audits · Second-life battery applications · Module & battery recycling · EPR compliance.
About the author

Chief Executive Officer, Growthifye — With over 23 years in management consulting, Sudarshan has taken businesses from concept to scale — building and scaling new-age digital and energy businesses.
- 23+ years in management consulting
- EY alumnus
- Led large-scale BESS programmes, capital raises and advisory mandates
Want this analysis applied to your project?
Talk to our team