Battery Collection Networks in India 2026: Economics, Safety and EPR Execution
By Sudarshan Karweer · sudarshan@growthifye.com · +91 84510 99371 (Call / WhatsApp) · 2026-08-30
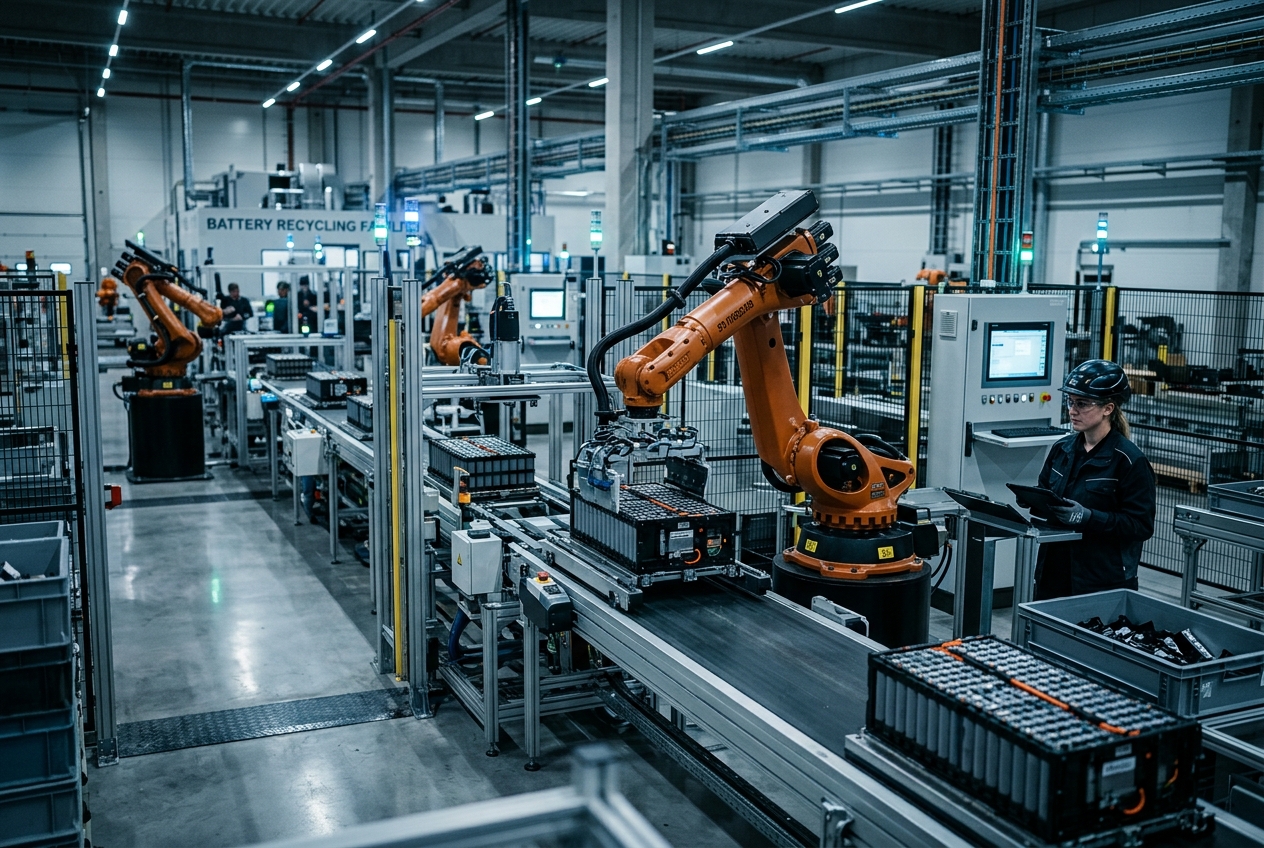
India’s battery circularity market in 2026 is increasingly defined by one operational question: who controls collection, aggregation and compliant movement of end-of-life batteries at scale? Recycling plants, black mass recovery lines and second-life screening assets receive attention, but project bankability often depends more on upstream feedstock control than downstream processing technology.
For Indian C&I consumers, EV fleet operators, OEMs, recyclers, developers and lenders, battery collection is no longer a back-office compliance task. It is a margin line, a safety function, an EPR execution challenge and, in many cases, the difference between utilisation above 70% and stranded recycling capacity.
This article focuses on a distinct angle within circularity: the design and economics of battery collection networks in India in 2026. The practical issues are channel mix, collection cost per kg, fire-safe handling, GST and invoicing discipline, transporter selection, state-level operating friction, digital traceability and contract structures that can survive audit scrutiny.
Why collection economics matters more in 2026
By 2026, India has more battery circularity participants than it had even two years ago: EV OEMs, battery pack assemblers, cell importers, producer responsibility organisations, informal aggregators, scrap traders, authorised recyclers, logistics firms and large users such as e-bus fleets, 3W financing platforms, telecom operators and C&I backup-power owners. The challenge is that collection remains fragmented while compliance expectations are rising.
A recycler may install 10,000-25,000 tonnes per annum of nameplate capacity, but if monthly compliant feedstock intake is volatile, the economics break quickly. Low utilisation inflates fixed-cost absorption, reduces chemical recovery consistency and weakens offtake contracting with downstream refiners.
In practice, three realities define 2026:
- feedstock is geographically dispersed and chemistry-mixed
- safe transport and storage standards are becoming lender and insurer concerns, not only regulatory concerns
- EPR targets increasingly require documented, traceable evidence rather than informal scrap procurement
For producers and obligated entities, the cost of poor collection design appears in multiple places:
- higher per-kg collection cost from sub-scale movements
- elevated rejection rates due to damaged, wet or mixed batteries
- fire incidents during storage or transit
- inability to prove EPR fulfilment during review
- price leakage to informal intermediaries
- lower realised recovery value because inbound batteries arrive degraded or dismantled incorrectly
This is why advisory work in End-of-life fleet audits and Reverse logistics is becoming central to circularity planning, especially for fleets and producers trying to build auditable sourcing channels.
India battery waste streams: not one market, but several
Talking about “battery collection” as one market is misleading. In India 2026, each waste stream behaves differently and requires a different network design.
The main streams are:
- EV 2W and 3W batteries: high volume, relatively dispersed, often channelled through dealer networks, service centres and local aggregators
- E-bus and commercial fleet packs: lower volume points, higher per-asset value, easier traceability, stricter handling needs
- Telecom and data-centre backup batteries: more structured ownership, better paperwork, often stronger competition for scrap value
- Inverter and residential storage batteries: highly fragmented, often influenced by kabadi and distributor channels
- Manufacturing scrap: lowest collection complexity, best traceability, usually preferred by recyclers for quality and predictability
- Imported defective or warranty-return units: documentation-heavy, often delayed by classification and logistics handling issues
Typical collection economics differ sharply by stream. Manufacturing scrap may move at under INR 4-8/kg in internal logistics-equivalent terms if generated near the recycling unit or pack plant. Dispersed small-format used batteries may cost INR 12-30/kg to collect and aggregate compliantly when accounting for field pickup, packaging, sorting losses, temporary storage and paperwork. Large-format EV pack pickup may be more expensive per pickup but often cheaper per kg because of density and recoverable value.
For many recycling projects, the key mistake is modelling blended feedstock procurement cost too optimistically. A spreadsheet using one average collection cost can hide severe viability gaps in geographically dispersed sourcing.
Cost stack for battery collection and aggregation
A practical 2026 collection model should separate procurement price from collection cost. These are not the same.
Procurement price refers to what the recycler or obligated producer pays for used batteries or scrap. Collection cost refers to everything required to move and aggregate material safely and compliantly.
A realistic collection cost stack may include:
- field sourcing commission or channel incentive
- pickup and first-mile transport
- UN-rated or equivalent safe packaging where applicable
- discharge, isolation, taping and terminal protection
- warehousing and aggregation point rent
- fire detection and suppression systems
- sorting and chemistry identification
- labour for inspection and segregation
- digital documentation and manifesting
- insurance and claims reserve
- shrinkage, theft or moisture damage allowance
- rejected material disposal cost
For dispersed lithium-ion collection, total delivered collection-and-aggregation cost in 2026 can range broadly from INR 15-40/kg depending on battery format, collection radius, quantity per pickup and safety protocol. For lead-acid the economics and regulatory handling are different, but even there formal players are under pressure to document flows more tightly.
For lenders assessing a recycling or circularity platform, one useful diligence question is this: what percentage of delivered feedstock cost is controllable through owned or contracted channel design, rather than spot buying? If that share is low, margin predictability is weak.
Collection hub sizing also matters. A city-level hub handling below 40-60 tonnes per month often struggles to absorb rent, compliance staffing and safety-system cost unless it is embedded in a larger service network. Conversely, overbuilding regional hubs too early can create idle fixed cost if producer tie-ups do not materialise.
EPR execution: compliance is increasingly operational
By 2026, EPR in India is no longer just a legal interpretation exercise. It is a data and operations exercise. Obligated entities need to show that collection and recycling flows are authentic, documented and attributable.
That means producer strategy must answer several practical questions:
- through which channels will returns be collected: dealers, service centres, fleet depots, aggregators, municipal links or direct pickup?
- who owns the customer relationship at end of life?
- how will batteries be tagged, reconciled and transferred?
- how will duplicate claims be prevented?
- who bears transport and storage liability before handover?
- how will non-traceable batteries be treated?
In 2026, the market is also seeing sharper differentiation between nominal collection claims and audit-ready collection evidence. Producers relying only on broad recycler assurances may find that internal audit, investor review or regulatory scrutiny requires a deeper chain-of-custody record.
This is where EPR compliance and Circularity reporting become commercially relevant capabilities rather than mere reporting tasks. Well-designed documentation systems can reduce disputes between producers and recyclers on attributable volume, recovery evidence and service fees.
A practical producer-side EPR operating model usually includes:
- a registered channel architecture with named collection points
- standard operating procedures for battery return acceptance
- tamper-minimised digital acknowledgement at handover
- batch-wise transport documentation
- chemistry and weight reconciliation at aggregation and recycler gate
- exception handling for damaged, swollen or recalled batteries
- periodic third-party verification for high-volume programs
For fleet operators, especially e-3W, e-bus and intralogistics fleets, EPR interaction is now part of asset-disposal planning. Battery replacement timing, warranty recovery, residual value and disposal route should be designed together rather than left to ad hoc scrap sale.
Safety and liability: the collection network can destroy value fast
Battery incidents in storage yards and transport vehicles continue to shape insurer and lender behaviour in 2026. Safety failure is not only a people-and-property risk; it can erase months of margin and damage permit credibility.
Common failure points in battery collection networks include:
- storing mixed chemistries without segregation
- inadequate state-of-charge management before transport
- damaged packs stacked without isolation
- no thermal monitoring in aggregation yards
- untrained labour opening packs for copper or aluminium recovery before safe processing
- weak incident response and no emergency tie-up with local fire services
For lithium-ion collection hubs, minimum practitioner discipline should include:
- chemistry-wise segregation
- quarantine area for damaged or suspect units
- insulated tools and PPE
- terminal insulation and non-conductive spacing
- thermal camera or equivalent monitoring for high-throughput sites
- clear no-dismantling rules unless the site is authorised and equipped
- documented emergency response protocol
Many insurers now ask more detailed questions on battery inventory profile, average dwell time, suppression systems and distance between stacks. A low-cost aggregator site can become expensive very quickly if insurance loading rises after an incident.
For utilities and C&I buyers engaging recyclers or collection partners, contract language should clearly allocate responsibility for pickup condition, packaging, title transfer, transit risk and incident reporting.
Channel strategy: own, partner or hybrid?
There is no single best battery collection model for India. The optimal structure depends on waste stream, geography and balance-sheet capacity.
The main approaches are:
- OEM-led network: suitable where service centres and dealers already exist; stronger traceability, but higher channel-management burden
- Recycler-led procurement network: faster scaling, but risk of variable documentation quality if subcontracted deeply
- PRO or compliance intermediary model: useful for aggregation and reporting, but must be tested for operational depth
- Fleet-direct model: best for large commercial fleets, easiest to audit, often strongest economics per kg
- Hybrid model: increasingly common, combining direct institutional sourcing with dealer and aggregator channels for retail flow
In 2026, the strongest networks are usually hybrid. They combine:
- anchor feedstock from fleets, telecom, OEM warranty returns or factories
- supplementary retail and service-centre collections
- regional hubs near major demand clusters such as NCR, Pune, Bengaluru, Chennai, Ahmedabad, Hyderabad and selected Tier-2 logistics corridors
The reason is simple: anchor volumes stabilise plant utilisation, while distributed channels improve EPR coverage and long-term market access.
Commercial contracts should address:
- minimum volume commitment or sourcing priority
- pricing formula by chemistry and state of condition
- contamination and moisture adjustment
- rejected-load responsibility
- payment timeline and GST treatment
- digital record obligations
- audit rights
- indemnity for non-compliant material handling
Spot procurement will remain part of the market, but projects financed on spot-heavy feedstock assumptions deserve a higher risk premium.
What developers, lenders and policymakers should watch in 2026
For project developers building circularity platforms, collection should be treated as infrastructure, not just sourcing. The questions are route density, hub placement, channel incentive design, safety capex, software traceability and working-capital discipline.
For lenders, the key diligence areas are:
- share of feedstock under contract versus spot purchase
- average delivered collection cost by stream, not only blended average
- evidence of channel attrition assumptions
- state-wise permit and storage compliance at hubs
- safety management systems and insurance adequacy
- data integrity in EPR-linked reporting
- counterparty concentration on both sourcing and recycling certificate value
For policymakers, the 2026 priority is not only target-setting but improving execution quality. Market confidence improves when compliant collectors and recyclers are not undercut by unsafe or undocumented channels. Better standardisation around collection-point operation, battery transport handling, digital reconciliation and fire-safety enforcement would reduce both compliance ambiguity and capital cost.
There is also a broader implication for India’s energy transition. As EV deployment, stationary storage and distributed power systems expand, circularity economics will increasingly affect lifecycle cost of energy assets. Strong collection systems lower feedstock uncertainty, improve domestic materials recovery and reduce environmental leakage.
That makes battery collection networks strategically important for more than recyclers alone. They matter to producers trying to meet obligations, to fleets trying to preserve residual value, to financiers trying to underwrite reliable cash flows and to utilities and policymakers trying to avoid unsafe waste accumulation.
In short, India’s circularity winners in 2026 will not be defined only by metallurgical recovery rates. They will be defined by their ability to source legally, move safely, document credibly and aggregate economically.
Growthifye works with market participants across circularity strategy, including End-of-life fleet audits, Reverse logistics, EPR compliance and Module & battery recycling. If you are evaluating collection-network design, recycler tie-ups, fleet battery disposition or circularity diligence, contact Growthifye’s advisory desk.
Explore Growthifye's related capabilities
This analysis connects directly to our advisory practice: End-of-life fleet audits · Second-life battery applications · Module & battery recycling · EPR compliance.
About the author

Chief Executive Officer, Growthifye — With over 23 years in management consulting, Sudarshan has taken businesses from concept to scale — building and scaling new-age digital and energy businesses.
- 23+ years in management consulting
- EY alumnus
- Led large-scale BESS programmes, capital raises and advisory mandates
Want this analysis applied to your project?
Talk to our team