Battery Collection Hubs in India 2026: Economics, Compliance and Network Design
By Sudarshan Karweer · sudarshan@growthifye.com · +91 84510 99371 (Call / WhatsApp) · 2026-08-30
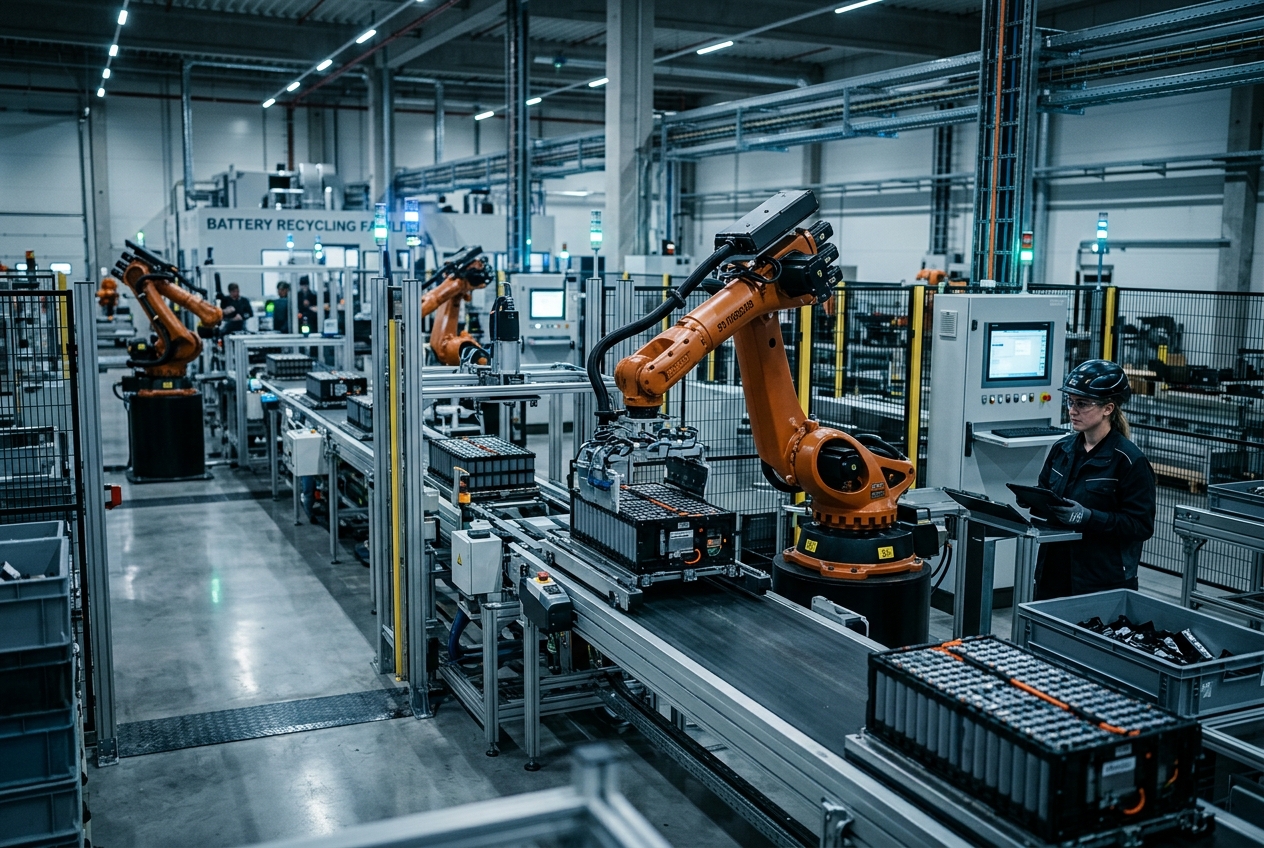
India’s battery recycling story is often told from the back end: shredding lines, hydromet recovery, black mass yields and recovered metal prices. In practice, the bigger execution risk in 2026 sits much earlier in the chain. If batteries are not identified, aggregated, made safe, documented and moved through compliant collection hubs, the downstream plant never sees stable throughput.
For OEMs, EV fleets, telecom tower operators, UPS-heavy commercial sites, e-rickshaw financiers, C&I energy users and recyclers, battery collection hubs are becoming the operating backbone of circularity. They are where economics, safety, EPR compliance, working capital and data integrity come together.
This article looks specifically at battery collection hubs in India in 2026: what they do, how much they cost, what throughput is needed, how regulations shape design, and how stakeholders should structure commercial models. This is a different question from recycling yields or second-life applications. It is about the physical and commercial node between waste generation and material recovery.
Why battery collection hubs matter in 2026
Three market shifts are making collection hubs strategically important.
First, battery scrap streams are diversifying. India now has lead-acid, LFP, NMC and smaller but rising volumes of LTO and niche chemistries moving through the market. Sources include 2W and 3W EV fleets, OEM service centres, inverter and telecom batteries, data centre backup systems, stationary storage pilots and consumer electronics channels. A single recycler cannot rely on ad hoc scrap procurement if it wants lender confidence on throughput.
Second, compliance expectations are tightening. The Battery Waste Management Rules, 2022 and subsequent implementation architecture under CPCB have pushed producers toward auditable take-back and recycling evidence. In 2026, informal aggregation still exists, but larger OEMs and serious recyclers increasingly need documented chain-of-custody, geotagged pickups, chemistry classification and evidence that material reached an authorised processor.
Third, logistics costs have become a margin driver. Collection is not simply transportation. It includes testing, segregation, discharging where required, damaged battery handling, temporary storage, packaging, insurance, manifests and dispute resolution over weight and quality. In many cases, poor collection design can destroy 8-15% of gross scrap value before material even reaches a recycler.
A well-designed hub network reduces landed input cost, lowers fire risk, improves data for EPR compliance and supports better commercial terms with suppliers. That is why OEMs and recyclers are now investing in Reverse logistics and hub-led aggregation models rather than relying only on trader networks.
What a battery collection hub actually does
A collection hub is not necessarily a recycling plant and should not be treated as one. Its role is controlled aggregation and dispatch.
At minimum, a functional hub in India should handle:
- Receipt and registration of incoming batteries or modules
- Basic inspection for swelling, leakage, external damage and chemistry identification
- Weight verification and reconciliation with supplier records
- Segregation by chemistry, state of damage and pack condition
- Temporary storage using fire-safe zoning and aisle separation
- Safe isolation of damaged or critical-risk units
- Packaging and dispatch preparation for recyclers, dismantlers or approved downstream processors
- Documentation for EPR and audit trails
Higher-maturity hubs may also perform:
- State-of-health screening to identify candidates for second-life evaluation
- Module-level sorting for packs with mixed residual value
- Discharge and energy neutralisation workflows where technically required
- QR or barcode-based traceability linked to producer responsibility records
- Commercial grading tied to chemistry, damage and contamination profile
This distinction matters because the capex, licensing pathway, staffing profile and insurance terms for a collection hub differ sharply from a full recycling unit. Many businesses overbuild on capex before they have enough predictable volume.
Economics: capex, opex and throughput benchmarks
In 2026, the economics of a battery collection hub in India depend primarily on chemistry mix, urban land cost, fire-safety requirements and dispatch radius.
For a small spoke hub serving one metro or industrial cluster, practical covered area may be 3,000 to 8,000 sq ft. For a regional aggregation hub, 10,000 to 25,000 sq ft is more realistic, especially where different chemistries and damaged units need separate zones.
Indicative capex ranges for a compliant spoke hub are as follows:
- Civil fit-out and segregation zones: Rs 12-25 lakh
- Fire detection, suppression, thermal cameras and alarms: Rs 10-30 lakh
- Racking, pallets, isolation bins and spill control: Rs 6-15 lakh
- Weighing, barcode, IT and traceability systems: Rs 4-12 lakh
- PPE, handling tools, insulated equipment and emergency kits: Rs 3-8 lakh
- DG backup, ventilation and electrical works: Rs 5-15 lakh
That puts a basic but serious spoke hub broadly in the Rs 40-90 lakh range, excluding land acquisition. A larger regional hub with higher safety redundancy, quarantine rooms and stronger digital traceability can move into the Rs 1.2-3 crore range.
Monthly opex typically includes:
- Rent or lease charges
- Trained operations team and EHS staff
- Security and 24x7 monitoring
- Insurance
- Packaging consumables and pallets
- Local transport coordination
- Digital platform subscriptions and record management
- Periodic safety audits and compliance costs
For a metro spoke hub, monthly opex may sit around Rs 4-10 lakh. A regional hub with stronger staffing and dispatch operations may run at Rs 10-25 lakh per month.
So what throughput makes sense?
A useful practitioner lens is cost per kg handled. Many operators target hub-level handling and storage cost below Rs 6-12/kg for relatively stable, non-damaged volumes and below Rs 15-25/kg for mixed and higher-risk streams requiring more intervention. If total network collection cost including first-mile pickup, storage and onward dispatch rises materially above recoverable value improvement, the model breaks.
For LFP-heavy 2W and 3W streams, procurement margins are already tight. A hub often needs 40-100 tonnes per month to negotiate transport and dispatch efficiently. For mixed chemistries and large packs from stationary systems or fleet operators, lower tonnage can still work because per-unit value and service fee potential are higher.
This is why network design matters more than simply adding more sites. In many states, a hub-and-spoke model with 1 regional node and 3-6 micro-aggregation points is more economical than multiple full-service hubs.
Compliance and licensing: where projects usually go wrong
In India, operators often underestimate the compliance complexity around temporary storage and handling of battery waste. The exact approval path depends on battery type, activity scope, state pollution control board interpretation, warehousing conditions and whether dismantling or pre-processing is taking place.
The core point for investors and operators is simple: a collection hub should be designed from day one as a compliance-first asset, not as a godown that later gets regularised.
Key 2026 compliance considerations include:
- Alignment with Battery Waste Management Rules, 2022 obligations and producer take-back architecture
- Authorisation requirements under applicable hazardous and other waste handling frameworks as interpreted by the relevant SPCB or PCC
- Record-keeping on inward and outward movement, source, chemistry and destination recycler
- Fire NOC and local authority approvals for storage of lithium-ion and damaged energy-storage units
- Worker safety protocols, PPE and incident response planning
- Packaging and transport requirements for damaged, defective or recalled units
- Contracts that define title transfer, liability and rejection procedures
One recurring issue is chemistry misclassification. Mixed lots received as "lithium battery scrap" often contain different chemistries, embedded electronics, metal contamination or damaged units. If the hub lacks trained classification staff, pricing disputes and safety events become more likely.
Another issue is storing charged batteries without proper isolation. Operators trying to save cost on discharge protocols, quarantine cages or thermal monitoring often face insurer resistance. In 2026, underwriters are increasingly asking detailed questions on storage density, damaged unit handling, emergency drills and maximum dwell time.
For companies building a serious network, EPR compliance should be embedded in system design rather than treated as a reporting exercise later. This is where digital intake, batch traceability and auditable reconciliations matter. Growthifye’s EPR compliance and Circularity reporting capabilities are particularly relevant for producers and aggregators trying to convert fragmented collection into a lender-grade operating system.
Commercial models for OEMs, recyclers and fleet operators
There is no single winning commercial structure. The best model depends on who controls scrap access and who carries price risk.
Common models in 2026 include:
- Producer-led captive hubs: OEM or battery producer contracts collection and dispatch while recycler provides downstream offtake assurance
- Recycler-led hubs: recycler establishes regional presence to secure feedstock directly and reduce dependence on traders
- Fleet or channel-partner hubs: large logistics, swap, telecom or e-rickshaw ecosystems aggregate batteries before auction or contracted sale
- 3PL-led managed hubs: specialist logistics or waste operators run the site under SLA-based arrangements
Commercial terms usually combine some of the following:
- Fixed service fee per kg collected or processed through the hub
- Revenue share linked to realised downstream value
- Minimum throughput commitment from producer or recycler
- Differential pricing for intact, damaged, mixed or contaminated lots
- Penalties for documentation gaps or rejected consignments
- Indexed pricing linked to chemistry and recoverable commodity value
For lead-acid, price discovery is relatively mature. For lithium-ion, especially LFP, a hub operator should avoid simplistic flat-rate contracts across all pack types. Recovery economics differ significantly by chemistry, condition and pack architecture. In some cases, the hub’s main value is not extracting a higher purchase price but lowering rejection, shrinkage and logistics cost.
Fleet owners and commercial battery users should also pay attention to residual-value leakage. Without structured collection, batteries are often sold through maintenance teams or local scrap channels with limited documentation. This may create apparent short-term recovery but can weaken EPR positions, insurance traceability and ESG disclosures.
A disciplined End-of-life fleet audits programme can uncover where batteries are arising, what conditions they are in, which depots create the most value leakage and whether second-life screening is commercially justified before recycling.
Network design: where should hubs be located?
Good hub siting in India is a function of scrap density, transport radius, safety response capability and recycler linkage.
The best locations in 2026 are not always the biggest metros. They are often peri-urban industrial corridors with lower lease cost, better truck access and proximity to fleet depots or service ecosystems. NCR, Pune belt, Ahmedabad-Vadodara corridor, Chennai belt, Hosur, Bengaluru outskirts, Hyderabad periphery and parts of Gujarat and Maharashtra remain attractive because of mixed industrial demand and logistics depth.
When evaluating a location, operators should test:
- Scrap generation within a 100-250 km radius by chemistry and source
- Access to highways and compliant transport vendors
- Fire response time and local emergency infrastructure
- Ability to maintain separation distances and ventilation
- Landlord willingness for battery-related use and insurance compatibility
- Distance to downstream recycler or dismantling facility
- Availability of trained staff
- Local regulatory responsiveness
A useful design principle is to avoid over-concentration of high-risk damaged units in one site unless specialised fire controls are in place. Another is to separate intake, quarantine, standard storage and dispatch staging physically, even in modest facilities.
Operators should also model dwell time aggressively. A collection hub is not a warehouse for indefinite stock accumulation. Longer dwell times increase insurance cost, fire risk and working-capital lock-up. Many successful operators target rapid turn cycles, especially for unstable or mixed-condition lithium-ion lots.
Strategic implications for lenders and policymakers
For lenders, battery circularity assets are often assessed through the lens of downstream recycling capacity. That is incomplete. Collection hubs deserve separate underwriting attention because they determine feedstock reliability and compliance quality.
Important diligence questions include:
- Is throughput contracted or merely assumed?
- What percentage of volume comes from anchor customers?
- How is chemistry risk managed?
- What is the maximum storage period by battery type?
- Are insurance and local approvals aligned with actual operating practice?
- How are title transfer and liability handled for damaged units?
- What data systems support traceability and EPR claims?
For policymakers, the next improvement frontier is interoperability and standardisation. Producers, recyclers and logistics operators still use fragmented classification, packaging and documentation formats. Standard digital schemas for collection events, chemistry tags, condition grading and transfer certificates could reduce disputes and improve auditability across states.
There is also a strong case for encouraging formal collection infrastructure near high-density EV and backup-power corridors rather than relying solely on end-stage recycling incentives. India’s circularity market will mature faster if the middle layer of safe aggregation becomes investable.
What industry participants should do now
In 2026, the practical roadmap is straightforward.
OEMs should map waste arisings by geography, service channel and chemistry before expanding EPR commitments.
Recyclers should treat hub economics as feedstock strategy, not auxiliary logistics.
Fleet operators and C&I energy users should stop assuming battery disposal is a procurement side issue and start integrating it into risk, compliance and residual-value planning.
Lenders should diligence the collection layer with the same seriousness they apply to recovery technology.
The winners in India’s battery circularity value chain will not only be those with the best metallurgical process. They will be those who can build compliant, safe, data-rich and economically disciplined collection networks that consistently move batteries from field to formal recovery.
If your organisation is planning battery take-back infrastructure, evaluating hub investments or tightening circularity controls across fleets and energy assets, contact Growthifye’s advisory desk. We support practical strategy and execution across Module & battery recycling, EPR compliance, Reverse logistics and related circularity programmes.
Explore Growthifye's related capabilities
This analysis connects directly to our advisory practice: End-of-life fleet audits · Second-life battery applications · Module & battery recycling · EPR compliance.
About the author

Chief Executive Officer, Growthifye — With over 23 years in management consulting, Sudarshan has taken businesses from concept to scale — building and scaling new-age digital and energy businesses.
- 23+ years in management consulting
- EY alumnus
- Led large-scale BESS programmes, capital raises and advisory mandates
Want this analysis applied to your project?
Talk to our team