
Merchant Tail Risk in Open Access PPAs India 2026: Pricing, Floors and Offtake Design
By Sudarshan Karweer · sudarshan@growthifye.com · +91 84510 99371 (Call / WhatsApp) · 2026-09-04
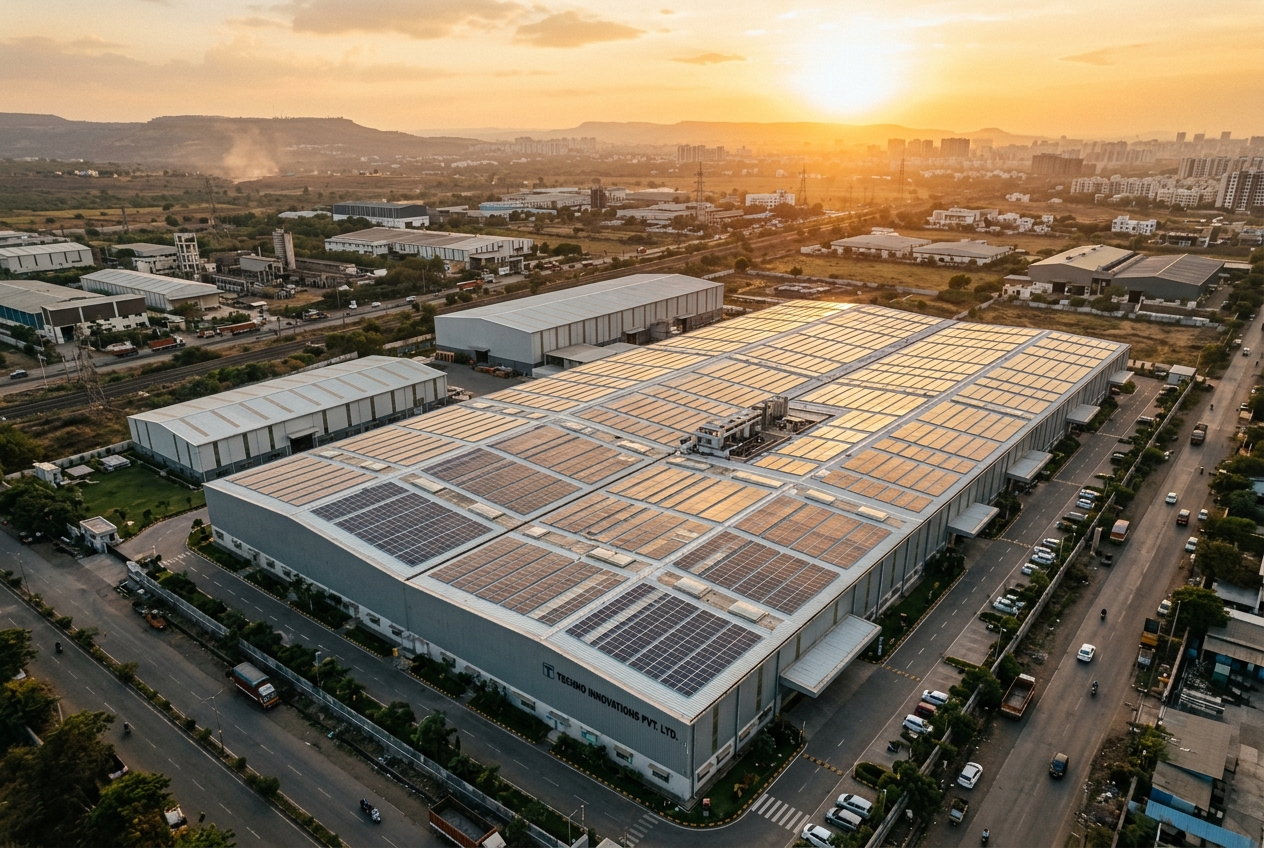
India’s open access market has matured on charges, banking and captive compliance. But one commercial issue still gets underpriced in many deals: merchant tail risk.
Merchant tail risk is the revenue and cost uncertainty associated with generation or contract periods that are not fully covered by the corporate buyer’s committed offtake at an agreed tariff. In practical terms, it shows up when a solar, wind or hybrid project generates more than the buyer can schedule or consume, when banking is restricted, when the buyer’s contracted volume is shaped differently from plant output, or when later years of a financing plan assume uncontracted sale at uncertain tariffs.
For C&I consumers, merchant tail risk matters because developers price it into the quoted PPA tariff, often implicitly. For developers and lenders, it affects DSCR stability, debt sizing and residual value assumptions. For utilities and policymakers, it influences whether open access projects are contracted on a realistic basis or simply transfer balancing risk into the system.
This article focuses on a distinct 2026 question: how to evaluate and structure merchant tail risk in Indian open access and corporate PPA transactions, especially for third-party and group captive projects where landed-cost economics depend not just on tariff, but on the fate of unsold or under-utilised energy.
What merchant tail risk means in Indian open access deals
In the Indian context, merchant tail risk has four common forms.
- Volume tail: the plant generates energy above the buyer’s committed annual or monthly drawal.
- Shape tail: the buyer’s load profile does not match the generation profile, creating excess injection in some blocks and shortages in others.
- Tenor tail: debt or equity returns rely on post-PPA or weakly contracted years.
- Regulatory tail: banking restrictions, scheduling rules, DSM treatment or sale-route constraints reduce monetisation of excess generation.
A simple example illustrates the issue.
Assume a 20 MW AC solar OA project in Rajasthan serving a C&I buyer with annual contracted offtake of 36 million kWh. At a 24% CUF, annual generation is around 42 million kWh. That leaves roughly 6 million kWh that must be managed through banking, additional consumers, exchange sale, utility purchase, or curtailment. If the base PPA tariff is Rs 3.05 per kWh and the developer’s alternative realisation for excess power is only Rs 2.20-2.60 per kWh after transaction costs, the weighted revenue stack is materially weaker than headline tariff suggests.
Now consider a wind project in Tamil Nadu with strong seasonal generation concentrated in monsoon months. If the buyer’s plant has flatter consumption and banking is restricted to monthly settlement without annual carry-forward, a large share of seasonal surplus may clear at low-value rates or lapse. The result is not just revenue loss for the generator; it can raise the buyer’s effective landed cost because the developer will quote a tariff that compensates for the expected spill.
Why merchant tail risk has become sharper in 2026
Three 2026 realities make this topic more important than it was a few years ago.
First, banking value has compressed in many states. Monthly settlement, time-of-day netting limits, banking charges, and restrictions on carry-forward have reduced the ability to smooth surplus generation across the year. Earlier, annual banking could absorb a large part of seasonal or diurnal mismatch. In many current structures, that is no longer true.
Second, C&I procurement teams are more sophisticated and often avoid over-contracting. Buyers increasingly contract only 60-90% of daytime demand in solar-led deals and leave residual demand to DISCOM supply, short-term purchase or green tariff products. This improves procurement flexibility, but can leave part of project output structurally uncovered unless the portfolio is carefully designed.
Third, lenders are tightening residual revenue assumptions. After seeing volatility in exchange prices, curtailment, and state-level OA rule changes, debt providers increasingly haircut merchant or quasi-merchant cash flows. A project whose base case relies on selling 10-20% of generation outside contracted offtake may face lower debt quantum or tougher reserve requirements.
Where the risk sits: buyer, developer or lender
Merchant tail risk is often misunderstood because parties discuss tariff before discussing allocation.
In a fixed-price physical OA PPA, the first question is: who takes the volume mismatch?
- If the buyer commits to take all delivered energy up to plant availability, merchant tail risk is lower for the developer but higher for the buyer, especially if load drops.
- If the buyer commits only to a scheduled quantum or a contracted capacity utilisation band, excess generation risk remains with the developer.
- If there is deemed generation, minimum offtake, or take-or-pay language, the risk transfer can become significant and must be tested against actual consumption variability.
For lenders, the relevant issue is not legal wording alone but realised cash flow after charges. A project selling contracted energy at Rs 3.10 per kWh may still underperform if 12% of net generation is repeatedly sold outside the PPA at Rs 2.25 per kWh while bearing forecasting, scheduling, SLDC and balancing frictions.
For buyers, the core question is whether they are paying a hidden premium in the tariff for a risk they could instead manage through better contract design, portfolio allocation or Demand & ToD analysis.
Quantifying merchant tail risk in landed-cost models
Merchant tail analysis should be explicit in every 2026 OA business case. A practical model should include at least the following variables.
- Contracted annual offtake in million kWh
- Monthly and ToD load profile of the buyer
- Net exportable generation after losses
- Banking rules: monthly or annual, settlement formula, banking charges
- CSS, AS, wheeling and transmission applicability by route
- Curtailment assumption by state and technology
- Alternate sale route and expected realisation for excess energy
- PPA floor, ceiling or balancing provisions
- Debt sizing haircut on merchant revenues
Consider an illustrative solar case for a Maharashtra C&I buyer.
- Net delivered generation potential: 50 million kWh/year
- Buyer willing to schedule: 44 million kWh/year
- Base PPA tariff: Rs 3.20/kWh
- Excess 6 million kWh sold externally at net Rs 2.35/kWh
- Weighted realisation: about Rs 3.10/kWh before some portfolio-level balancing effects
If the developer wants to preserve target equity IRR, it may seek to quote Rs 3.28-3.35/kWh instead of Rs 3.20/kWh in a fully matched contract. The buyer may compare only the quoted tariff and miss that the difference is driven by uncovered generation risk.
Now compare this with a better-shaped offtake arrangement:
- Contracted offtake increased to 47 million kWh/year
- One additional affiliated load added for weekend daytime absorption
- Monthly banking utilisation improved by 2-3 percentage points
- Excess volume reduced to 3 million kWh/year
In that case, the quoted tariff could reduce by 8-18 paise/kWh, depending on state charges and expected merchant realisation. On large annual consumption, that is meaningful.
This is why Landed-cost management cannot stop at tariff benchmarking. It must isolate mismatch costs, monetisation assumptions and fallback sale options.
Contract structures that reduce merchant tail exposure
There is no single template, but several structures are working better in 2026 than a plain fixed tariff with vague excess-energy wording.
1. Contracted energy bands
Instead of an imprecise “entire generation” concept, define annual and monthly energy bands.
- Base contracted band: for example 85-90% of P50 generation
- Optional offtake band: additional energy the buyer may schedule at PPA tariff or a discount formula
- Excess beyond upper band: developer free to sell elsewhere
This avoids disputes and prevents buyers from inadvertently paying for uncertain top-end generation.
2. Floor price for developer’s excess sale assumption
Where tariff is built on expected monetisation of uncovered energy, parties can agree a reference floor methodology. This is more common in negotiated captive or anchor-consumer deals.
For example:
- Tariff assumes excess sale realisation of Rs 2.40/kWh
- If realised value falls below Rs 2.10/kWh due to specified market reasons, parties share downside through a pre-agreed true-up cap
- If realised value exceeds a threshold, upside is shared with the buyer through rebate or annual credit
This is more complex than a standard OA PPA, but can materially improve bankability in projects with unavoidable residual volume.
3. Multi-offtaker allocation
A single-buyer OA project often carries concentrated tail risk. A two- or three-buyer structure can improve shape matching.
- Day-load manufacturer as anchor
- Commercial campus with weekday peak overlap
- Seasonal auxiliary industrial load
A portfolio with complementary load curves can absorb generation that would otherwise clear at low merchant value. Growthifye’s Sourcing strategy and Competitive developer selection work often uncovers value here that a one-buyer tender misses.
4. Technology shaping
Hybridisation is not only about RTC. In some states, adding a modest wind share to solar, or limited storage for intraday shifting, improves offtake alignment enough to reduce spill and strengthen revenue quality.
Even when hybrid power has a higher apparent tariff, it can lower all-in procurement cost if it reduces expensive excess generation and replacement power in non-solar hours.
5. Tenor alignment and residual-value discipline
If debt tenor is 12-14 years but committed offtake visibility is strong only for 8-10 years, the last tranche of value must not be treated casually. Residual years should be stress-tested at conservative tariffs, not optimistic escalation-led assumptions.
For lender cases in 2026, it is prudent to test at least:
- Base case merchant sale after contract at Rs 2.25-3.00/kWh depending on state and technology
- Delayed sale route availability
- Lower plant output due to degradation and curtailment
- Higher evacuation and scheduling frictions
State and route differences that change the answer
Merchant tail risk is not uniform across India.
A few practical 2026 observations:
- In states with tighter banking settlement and limited carry-forward, seasonal wind surplus is harder to monetise.
- In cross-state deals, ISTS route economics may look attractive on contracted energy but become weaker if excess power cannot be efficiently allocated to additional consumers.
- In some same-state solar deals, a large industrial day load can nearly eliminate merchant tail and support very competitive tariffs.
- Group captive structures may reduce landed charges relative to third-party supply in some cases, but if captive users’ consumption fluctuates and 26% ownership or 51% annual consumption planning is weak, uncovered energy can still create economic leakage.
This is why a state- and route-specific memo is essential before locking tariff. A developer quote that is attractive in Karnataka may be inferior in Gujarat or Tamil Nadu once mismatch monetisation is fully modelled.
A due-diligence checklist for buyers, developers and lenders
Before signing an OA PPA in 2026, ask these questions.
- What percentage of P50 and P90 generation is fully contracted by month, not just by year?
- What is the expected value of excess energy after all route-specific charges and losses?
- Is merchant value based on exchange sale, utility purchase, affiliate allocation or unspecified assumptions?
- How much tariff premium is embedded for mismatch risk?
- What happens if the buyer’s load drops 10-15% because of production changes?
- Is there a right to add replacement consumers or group entities?
- Are scheduling and forecasting obligations clearly allocated?
- Does the financing case rely on terminal or tail-year assumptions that are too aggressive?
- Are monthly DSM, banking and settlement impacts included in the landed-cost model?
For serious transactions, these points should appear in the investment committee paper, not remain buried in annexures.
The 2026 takeaway: price the hidden volume, not just the headline tariff
Open access procurement is no longer only about securing a low nominal tariff. The real economic contest is between well-shaped contracted energy and poorly monetised excess energy.
In many Indian C&I deals, a tariff difference of 10-20 paise/kWh can be entirely explained by how merchant tail risk is handled. Buyers that ignore this may overpay for perceived certainty. Developers that ignore it may win capacity but lose cash flow quality. Lenders that underwrite it loosely may discover that DSCR pressure emerges not from plant underperformance, but from volume that was never truly contracted.
The right answer is not to eliminate all residual risk. It is to identify it, model it by month and time block, and assign it to the party best able to manage it. That is where disciplined PPA structuring & negotiation creates measurable value.
If your organisation is evaluating an open access or corporate PPA in 2026 and wants an independent view on merchant tail exposure, offtake shaping, charges and landed economics, contact Growthifye’s advisory desk.
Explore Growthifye's related capabilities
This analysis connects directly to our advisory practice: Demand & ToD analysis · Sourcing strategy · Competitive developer selection · PPA structuring & negotiation.
About the author

Chief Executive Officer, Growthifye — With over 23 years in management consulting, Sudarshan has taken businesses from concept to scale — building and scaling new-age digital and energy businesses.
- 23+ years in management consulting
- EY alumnus
- Led large-scale BESS programmes, capital raises and advisory mandates
Want this analysis applied to your project?
Talk to our team

