India Pumped Hydro 2026: Site Screening, Tariffs, Risks and Bankability
By Sudarshan Karweer · sudarshan@growthifye.com · +91 84510 99371 (Call / WhatsApp) · 2026-08-30
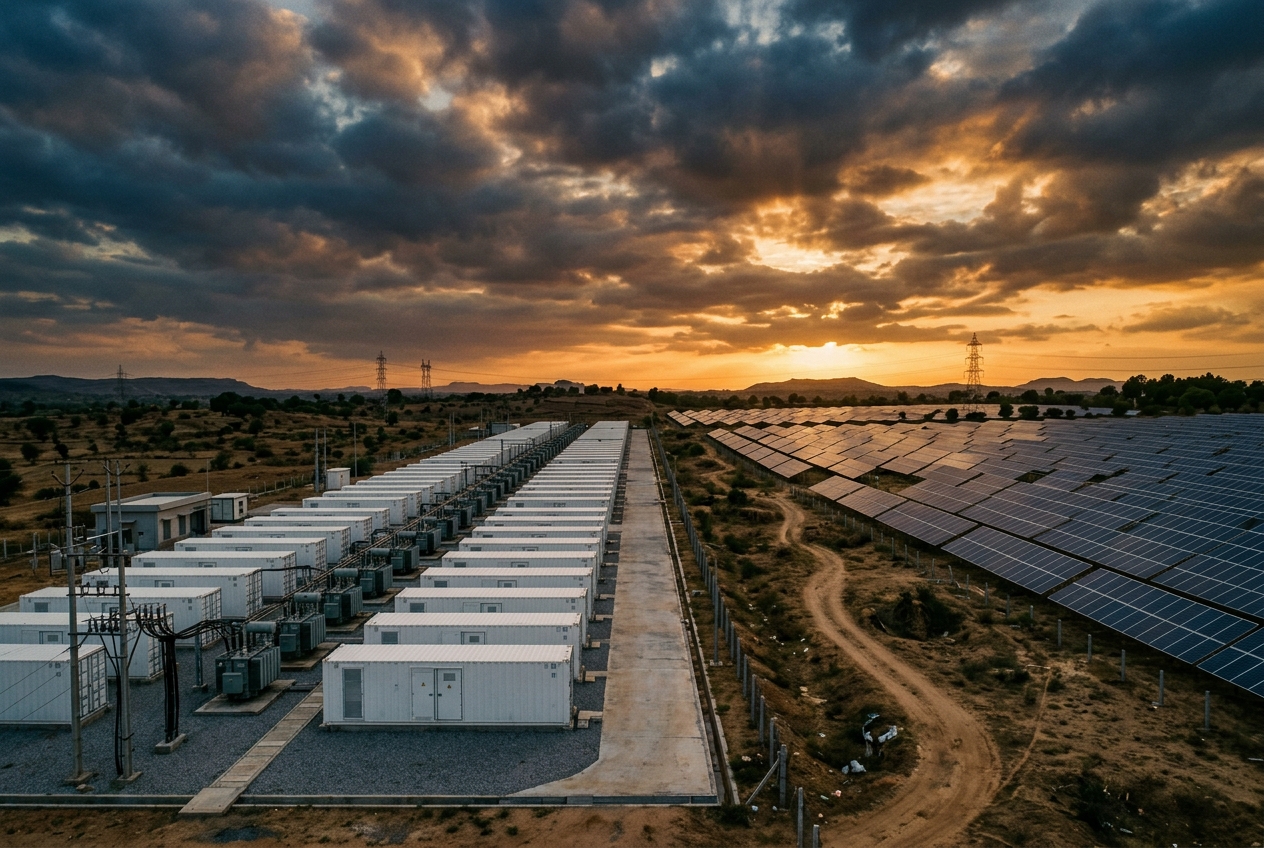
India’s storage discussion in 2026 is heavily focused on battery energy storage systems, ancillary markets and hybrid tenders. Yet pumped hydro storage (PHS) is again moving into the mainstream for a different reason: duration, system value and long-asset life. For state utilities, central procurers, RE developers and large industrial buyers thinking about firm power, pumped hydro is no longer a legacy technology story. It is a portfolio, grid-balancing and financing question.
The immediate opportunity is not that pumped hydro will replace batteries. It will not. The more relevant point is that India’s power system increasingly needs both short-duration flexibility and deep-shifting capacity. Solar-heavy daytime generation, evening ramps, monsoon variability, thermal cycling constraints, renewable energy integration targets and round-the-clock supply obligations create a role for long-duration storage that can move large blocks of energy reliably over decades.
For developers and lenders, however, the commercial viability of pumped hydro is much more site-specific and contract-specific than many policy headlines suggest. A 1,000 MW project with 6 to 10 hours of storage may look compelling on a system-planning slide, but the bankable question remains simple: what is the delivered tariff, under which offtake structure, with what hydrology, geology, construction and transmission risks?
This article examines pumped hydro in India in 2026 from a practitioner lens: site screening, use cases, cost ranges, tariff formation, approvals and lender concerns.
Why pumped hydro is back in India’s storage mix
The case for pumped hydro in India has strengthened because the grid’s flexibility requirement is increasing faster than conventional balancing options are improving.
Three trends matter most:
- Renewable penetration keeps rising, especially solar additions with low daytime variable cost.
- Peak demand is growing in absolute terms, with sharper evening net-load ramps in several states.
- Thermal fleets are being asked to cycle more often, even though many units were not designed for frequent deep ramping.
In this context, pumped hydro offers a different value proposition from lithium-ion BESS:
- 6 to 10+ hour discharge durations are feasible at utility scale.
- Asset life can extend to 40 to 60 years with appropriate refurbishment cycles.
- Round-trip efficiency is typically lower than BESS, but system-level value can still be strong for deep energy shifting and peak support.
- Variable storage cost over long durations can be attractive relative to adding batteries hour after hour for the same output block.
For India, pumped hydro is especially relevant for:
- evening peak firming of solar-heavy portfolios
- RTC and FDRE supply configurations requiring long-duration balancing
- reserve support and contingency flexibility at scale
- seasonal and monsoon-related renewable output management in some systems
- replacing part of expensive peaking thermal generation or market purchases
That said, pumped hydro is not a generic answer. The project must clear four hurdles simultaneously: suitable topography, manageable approvals, viable transmission evacuation and a contracted revenue model that supports high upfront capex with long construction periods.
The project configurations that are commercially relevant in 2026
In India’s current market, not every pumped hydro configuration is equally financeable. The most relevant structures are the following.
1) Standalone pumped hydro with long-term utility offtake
This is the most straightforward bankability route where a state utility, central agency or bulk buyer contracts capacity and/or energy over a long tenor. The project may charge using grid power during off-peak hours and discharge during contracted peak windows.
Commercial viability depends on the spread between pumping energy cost and delivered peak value, plus any capacity-style payment that recognises storage availability.
2) Renewable-plus-pumped-hydro bundled supply
Here, a developer combines solar, wind or hybrid RE with pumped hydro to deliver a shaped output profile. This structure becomes relevant for:
- FDRE-style supply obligations
- high-CUF products
- evening and night-time firming
- state utility demand for dispatchable renewable energy
Compared with battery-based hybrids, pumped hydro can be attractive for longer-duration firming. But transmission design, energy accounting and pumping-power sourcing become more complex.
3) Merchant or partially merchant peak arbitrage
This is conceptually possible but still harder to finance in India unless there is substantial contracted support. Pure merchant exposure requires confidence in sustained time-of-day spreads, balancing prices or capacity scarcity value. In 2026, most domestic lenders are still more comfortable with visible contracted cash flows than with a largely speculative price-arbitrage thesis over a 40-year asset life.
4) State-backed strategic storage assets
Some pumped hydro projects are being advanced because they solve system-level balancing constraints for a state or regional grid. In these cases, the offtake logic may be closer to an infrastructure planning decision than a pure merchant-generation investment decision.
Site screening: where pumped hydro projects succeed or fail
The biggest mistake in pumped hydro development is to start with headline megawatts instead of site fundamentals. In practice, the project is won or lost at site-screening stage.
A workable screening framework in 2026 should include the following.
Topography and head
The site needs enough elevation difference between upper and lower reservoirs to create commercially useful head. Higher head can reduce the water volume required for a given energy capacity, but it also affects civil design complexity and equipment selection.
As a practical matter, developers assess:
- gross and net head ranges
- reservoir geometry
- tunnel and penstock alignment feasibility
- access for heavy equipment and construction logistics
Water availability and hydrology
Closed-loop pumped hydro is receiving more attention because it can reduce some river-related environmental and operational risks. But even closed-loop systems need robust water-balance assessment.
The key questions are:
- initial filling requirement
- annual replenishment needs due to evaporation and seepage
- catchment interaction and flood management
- competing water-use constraints
A weak hydrology case can delay approvals or undermine operations, especially in water-stressed states.
Geology and geotechnical risk
This is one of the largest hidden bankability issues. Underground works, slope stability, excavation conditions and foundation quality can materially alter capex and schedule.
Lenders will typically focus on:
- adequacy of geotechnical investigations
- tunnelling risk allocation in EPC contracts
- contingency assumptions for adverse rock conditions
- design maturity before debt drawdown
A pumped hydro project with shallow preliminary surveys but aggressive capex assumptions will struggle in credit committees.
Land and social interface
Even when a site appears topographically attractive, land aggregation, forest interface, rehabilitation exposure and local access constraints can delay the project by years.
Developers should screen early for:
- private versus government land mix
- forest land diversion requirements
- habitation impacts
- local water-use sensitivities
- road and construction-camp footprint
Grid connectivity and transmission evacuation
Storage is only valuable if it can charge and discharge when needed. A pumped hydro project far from strong substations may face avoidable transmission capex and losses.
Key parameters include:
- distance to pooling or ISTS/state transmission nodes
- import capability for pumping load
- export capability during peak discharge
- congestion conditions in likely operating windows
- metering and scheduling architecture for storage operations
For many projects, transmission readiness is as important as civil feasibility.
Capex, duration and tariff logic in 2026
Pumped hydro economics cannot be judged using a single Rs/kWh number without context. The right commercial lens is a combination of:
- Rs crore/MW for power block and civil works
- storage duration in hours
- round-trip efficiency
- pumping energy cost
- annual cycle profile
- auxiliary consumption
- construction period and IDC
- offtake tariff design
In the 2026 Indian market, broad capex discussion ranges for utility-scale pumped hydro often sit around Rs 8 crore/MW to Rs 14 crore/MW for many announced concepts, but actual all-in project costs can move well outside that range depending on geology, reservoir works, transmission scope, land, IDC and execution complexity. Greenfield projects with significant underground works or difficult access can trend higher.
Duration usually matters more than many early-stage models admit. A 1,000 MW, 8-hour facility implies 8,000 MWh of usable discharge capability before accounting for losses and operational constraints. That long-duration characteristic is the core differentiator relative to shorter-duration BESS configurations.
Round-trip efficiency for pumped hydro commonly falls below lithium-ion alternatives, often in the broad 70% to 80% band depending on design and operations. But for peak-shifting applications where off-peak charging energy is inexpensive and the peak-value spread is strong, lower efficiency does not automatically make the project uneconomic.
Tariff design in India generally needs to recognise at least one of the following:
- capacity availability value
- n- energy shifting value
- peak-period supply value
- grid support and flexibility value
If a project is paid only on discharged energy while bearing high fixed capital cost and long construction risk, tariff pressure can become severe. Many viable structures therefore need a two-part logic, even if not explicitly labelled that way in procurement documents.
As a practical benchmark, delivered tariffs for bundled renewable-plus-storage supply must compete with alternatives available to utilities. If the all-in shaped power price moves too far above the utility’s avoided cost of thermal, hydro, market purchases and shorter-duration BESS-based balancing, the project loses competitiveness. This is why pumping-energy sourcing strategy is central to financial modelling.
Approvals, contracting and construction risks
The Indian pumped hydro pipeline is growing, but development timelines remain exposed to multiple clearances and interface risks.
Typical approval tracks may include:
- state government support and allotment processes
- environmental and forest clearances where applicable
- water-use permissions
- geological and survey approvals
- transmission connectivity approvals
- electrical approvals and grid studies
From a contracting perspective, lenders and sponsors should pay close attention to package strategy. A single wrap EPC contract can look neat on paper, but few contractors are comfortable taking unlimited geology and underground execution risk at fixed price. Multi-package strategies may be more realistic but create interface risk.
Critical contract issues include:
- geological risk sharing
- delay damages and force majeure treatment
- performance guarantees for efficiency and availability
- tunnelling and excavation quantity variation mechanisms
- reservoir integrity and seepage responsibilities
- testing and commissioning standards
Construction periods can run materially longer than utility-scale battery projects. That means interest during construction, cost escalation and permitting delays have much larger consequences for project IRR and debt service profile.
What lenders and investors will actually examine
In 2026, lenders are willing to engage with pumped hydro, but credit appetite depends on disciplined project preparation rather than storage optimism.
The most important diligence questions are usually the following:
Is the offtake structure strong enough?
A credible long-term offtaker, payment security framework and dispatch logic matter more than ambitious merchant price assumptions. Utility credit quality and state payment behaviour remain important.
Is the site genuinely de-risked?
Desktop potential is not enough. Lenders will want advanced surveys, geotechnical evidence, realistic hydrology, land visibility and transmission clarity.
Are cost estimates mature?
Early-stage pumped hydro cost numbers are often too optimistic. Sensitivity testing should include:
- capex overruns
- one- to two-year schedule delays
- lower-than-expected annual cycling
- pumping power cost escalation
- reduced availability in early operating years
Does the tariff absorb long construction risk?
If the revenue model does not compensate for the construction profile and fixed-cost nature of the asset, leverage will be constrained or returns will not clear sponsor thresholds.
How does the asset compete with BESS over time?
This is a strategic question, not just a technical one. In some 2- to 4-hour applications, BESS may remain the better answer due to speed, modularity and falling system costs. Pumped hydro becomes more compelling where duration, cycle depth and very long asset life create a system advantage.
Where pumped hydro fits in India’s 2026 power market
The strongest commercial case for pumped hydro today is not generic storage procurement. It is targeted deployment where long-duration flexibility solves a real power-system or portfolio problem.
The most bankable use cases are likely to be:
- state utility peak management with defined peak/off-peak spread
- large renewable portfolios requiring 6+ hour shaping
- central or state procurement of dispatchable clean power blocks
- strategic balancing assets in systems facing steep evening ramps
The weakest cases remain:
- poorly surveyed sites advanced mainly on capacity ambition
- projects assuming aggressive merchant arbitrage without contracted support
- projects with unresolved transmission import/export constraints
- tariff bids that underprice geology, schedule and financing risk
For policymakers, the lesson is clear. If India wants pumped hydro to scale meaningfully, procurement design must recognise duration value and availability value rather than treating all storage as interchangeable. For developers, the message is equally clear: site quality and contract design matter more than headline megawatts. For lenders, disciplined screening can separate strategic infrastructure from speculative pipeline noise.
Pumped hydro will not be the answer everywhere. But in the right locations, under the right contract structure, it can become one of the most durable storage assets in India’s transition from energy-only renewable additions to dispatchable clean power.
If you are evaluating a pumped hydro opportunity, need support on site screening, tariff modelling, offtake strategy or lender diligence, contact Growthifye’s advisory desk.
About the author

Chief Executive Officer, Growthifye — With over 23 years in management consulting, Sudarshan has taken businesses from concept to scale — building and scaling new-age digital and energy businesses.
- 23+ years in management consulting
- EY alumnus
- Led large-scale BESS programmes, capital raises and advisory mandates
Want this analysis applied to your project?
Talk to our team