Kochi rates, per sq ft carpet.
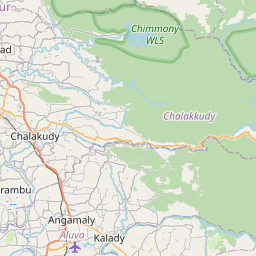
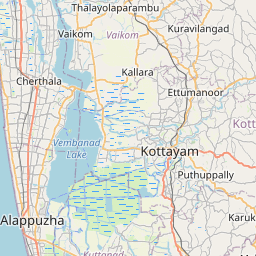

Pin = market rate, ₹/sq ft carpet. Click a pin to load it into the land-cost calculator.
| Micro-market | Market ₹/sq ft | Reckoner | Premium | Rent ₹/sq ft/mo | Yield · typical |
|---|---|---|---|---|---|
| Marine Drive – MG Rd Central business district | ₹12,510 | ₹7,700 | +62.5% (+3.3% vs city line) | ₹25 | 2.4% 2 BHK ₹23,800/mo |
| Panampilly Nagar Prime residential | ₹11,080 | ₹7,240 | +53% (-1.9% vs city line) | ₹24.9 | 2.7% 2 BHK ₹23,700/mo |
| Edappally – Kaloor Prime residential | ₹8,850 | ₹5,790 | +52.8% (+1.3% vs city line) | ₹19.9 | 2.7% 2 BHK ₹18,900/mo |
| Fort Kochi – Mattancherry Established mid-market | ₹7,510 | ₹5,250 | +43% (-3.5% vs city line) | ₹19.4 | 3.1% 2 BHK ₹18,400/mo |
| Vyttila – Thripunithura Established mid-market | ₹7,130 | ₹5,040 | +41.5% (-3.7% vs city line) | ₹18.4 | 3.1% 2 BHK ₹17,500/mo |
| Kakkanad Established mid-market | ₹6,880 | ₹4,760 | +44.5% (-0.5% vs city line) | ₹17.8 | 3.1% 2 BHK ₹16,900/mo |
| Aluva – Kalamassery Peripheral / emerging | ₹4,530 | ₹3,400 | +33.2% (+0.5% vs city line) | ₹14 | 3.71% 2 BHK ₹13,300/mo |
| Nedumbassery – Angamaly Peripheral / emerging | ₹3,830 | ₹2,870 | +33.4% (+7.3% vs city line) | ₹11.8 | 3.7% 2 BHK ₹11,200/mo |
Land cost calculator — acquisition, stamp duty & TDR
Type a plot size; we apply the micro-market land rate, the state's stamp-duty rule (charged on the higher of market and reckoner value) and the local TDR pricing convention.
Acquisition (market)
₹8.80 cr
₹2,020/sq ft × 43,560 sq ft
Stamp duty + registration
₹88.0 lakh
8% + 2% on ₹8.80 cr
Total outlay
₹9.68 cr
₹1,111 per buildable sq ft @ FSI 2
Kerala: 8% stamp + 2% registration on fair value. Indicative — confirm with the sub-registrar's current schedule.
Vidura market brief
Kochi's residential market continues to trade well above IGR Kerala's Fair Value benchmarks across all micro-markets, with city-wide appreciation tracking near 5.5% YoY. Marine Drive–MG Road commands the steepest premium at 62.5% (₹12,510 vs ₹7,700/sq ft), followed by Panampilly Nagar at 53% and Edappally–Kaloor at 52.8%, reflecting concentrated demand for central, transit-connected addresses. Peripheral corridors—Aluva–Kalamassery and Nedumbassery–Angamaly—hold tighter premiums near 33%, closer to reckoner parity, making them comparatively efficient for land acquisition and large-footprint PPP projects where circle-rate-linked compensation and stamp duty costs matter most. For investors, this spread signals where asset monetisation yields the strongest arbitrage (core micro-markets) versus where greenfield infrastructure or housing PPPs face lower entry friction (outer corridors along the airport-industrial belt). As Kochi's tier-2 momentum draws broader capital inflows, expect peripheral zones near Kakkanad and Angamaly to gradually re-rate as infrastructure spending narrows the premium gap with the core.
Generated 2026-10-26 from the engine's current numbers and recent headlines · refreshed weekly
5-year trend — city average, residential
Lime = engine's city average sale · sky = rent ₹/sq ft/month · dashed blue = YoY % · amber dots = credible prints (CRE Matrix / PropEquity / Knight Frank / IGR headlines, team deals) — 0 so far · 5Y sale +16.1% · rent +16%
- rent
- value
- yoy
Reckoner ↔ market correlation
market ≈ −₹1,510.2 + 1.7694 × reckoner · R² 0.993 · n = 8 micro-markets
Points above the line are micro-markets where the market has run further ahead of the government rate — expect higher land-acquisition cost and stamp-duty arbitrage; points below signal reckoner catch-up risk.
Recent public signals
Indicative desk estimates calibrated to government reckoner/circle rates and public signals; not a valuation. Refined daily and by team corrections. Reckoner source: IGR Kerala — Fair Value of Land. Unit: ₹ per sq ft carpet (land: ₹ per sq ft of plot).