Ahmedabad rates, per sq ft carpet.
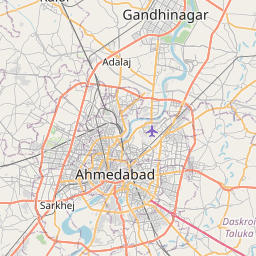

Pin = market rate, ₹/sq ft carpet. Click a pin to load it into the land-cost calculator.
| Micro-market | Market ₹/sq ft | Reckoner | Premium | Rent ₹/sq ft/mo | Yield · typical |
|---|---|---|---|---|---|
| West · 5 | |||||
| SG Highway – Bodakdev Central business district | ₹9,500 | ₹5,850 | +62.4% (+5.9% vs city line) | ₹19 | 2.4% 2 BHK ₹18,000/mo |
| Satellite – Prahlad Nagar Prime residential | ₹8,810 | ₹5,790 | +52.2% (-0.6% vs city line) | ₹19.8 | 2.7% 2 BHK ₹18,800/mo |
| Vastrapur – Thaltej Prime residential | ₹8,520 | ₹5,590 | +52.4% (0% vs city line) | ₹19.2 | 2.7% 2 BHK ₹18,200/mo |
| Ambli – Shilaj Prime residential | ₹8,200 | ₹5,400 | +51.9% (+0.1% vs city line) | ₹18.4 | 2.69% 2 BHK ₹17,500/mo |
| Bopal – South Bopal Established mid-market | ₹6,170 | ₹4,340 | +42.2% (-3% vs city line) | ₹15.9 | 3.09% 2 BHK ₹15,100/mo |
| North · 2 | |||||
| GIFT City – Gandhinagar Established mid-market | ₹7,520 | ₹5,250 | +43.2% (-5.2% vs city line) | ₹19.4 | 3.1% 2 BHK ₹18,400/mo |
| Chandkheda – Motera Established mid-market | ₹5,180 | ₹3,640 | +42.3% (+0.6% vs city line) | ₹13.4 | 3.1% 2 BHK ₹12,700/mo |
| North-West · 1 | |||||
| Gota – Jagatpur Growth suburb | ₹4,880 | ₹3,570 | +36.7% (-2.9% vs city line) | ₹13.8 | 3.39% 2 BHK ₹13,100/mo |
| South-West · 2 | |||||
| Shela – Sanand Rd Growth suburb | ₹4,780 | ₹3,490 | +37% (-2.2% vs city line) | ₹13.5 | 3.39% 2 BHK ₹12,800/mo |
| Sanand – Changodar Peripheral / emerging | ₹3,220 | ₹2,420 | +33.1% (+5.9% vs city line) | ₹9.9 | 3.69% 2 BHK ₹9,400/mo |
| East & South · 2 | |||||
| Maninagar – Isanpur Established mid-market | ₹4,750 | ₹3,360 | +41.4% (+1.8% vs city line) | ₹12.3 | 3.11% 2 BHK ₹11,700/mo |
| Naroda – Vastral Peripheral / emerging | ₹3,630 | ₹2,720 | +33.5% (+2% vs city line) | ₹11.2 | 3.7% 2 BHK ₹10,600/mo |
Land cost calculator — acquisition, stamp duty & TDR
Type a plot size; we apply the micro-market land rate, the state's stamp-duty rule (charged on the higher of market and reckoner value) and the local TDR pricing convention.
Acquisition (market)
₹57.28 cr
₹13,150/sq ft × 43,560 sq ft
Stamp duty + registration
₹3.38 cr
4.9% + 1% on ₹57.28 cr
Total outlay
₹60.66 cr
₹6,963 per buildable sq ft @ FSI 2
Gujarat: 4.9% + 1% registration (nil registration for women). TDR under GDCR. Indicative — confirm with the sub-registrar's current schedule.
Vidura market brief
Ahmedabad's residential market continues to trade well above Garvi jantri rates across all tracked micro-markets, with premiums ranging from 33% to over 62%, reinforcing a widening valuation gap that materially affects land acquisition costs for infrastructure and PPP projects. SG Highway–Bodakdev commands the steepest premium at 62.4% (₹9,500 vs ₹5,850/sq ft), followed closely by Vastrapur-Thaltej and Satellite-Prahlad Nagar at roughly 52%, reflecting established connectivity, social infrastructure and sustained end-user demand in these western corridors. This premium concentration matters for PPP viability: reckoner-based compensation under land acquisition frameworks will significantly undervalue parcels in these zones, inflating resettlement costs and litigation risk, while asset monetisation (TOD, land parcels adjoining transit corridors) in premium micro-markets offers superior revenue potential per acre. Peripheral zones like Sanand-Changodar and Naroda-Vastral show comparatively compressed premiums (~33%), making them more tractable for large-footprint infrastructure assembly. With YoY appreciation tracking near 6.5% and GIFT City anchoring institutional-grade demand, expect the reckoner-market gap to widen further, necessitating periodic jantri revisions to keep acquisition economics viable.
Generated 2026-10-26 from the engine's current numbers and recent headlines · refreshed weekly
5-year trend — city average, residential
Lime = engine's city average sale · sky = rent ₹/sq ft/month · dashed blue = YoY % · amber dots = credible prints (CRE Matrix / PropEquity / Knight Frank / IGR headlines, team deals) — 0 so far · 5Y sale +18.8% · rent +19.2%
- rent
- value
- yoy
Reckoner ↔ market correlation
market ≈ −₹1,142.8 + 1.7284 × reckoner · R² 0.989 · n = 12 micro-markets
Points above the line are micro-markets where the market has run further ahead of the government rate — expect higher land-acquisition cost and stamp-duty arbitrage; points below signal reckoner catch-up risk.
Recent public signals
Indicative desk estimates calibrated to government reckoner/circle rates and public signals; not a valuation. Refined daily and by team corrections. Reckoner source: Garvi — Jantri Rates. Unit: ₹ per sq ft carpet (land: ₹ per sq ft of plot).