India Solar Module Technology Selection 2026: TOPCon, HJT, ALMM and EPC Guide
By Sudarshan Karweer · sudarshan@growthifye.com · +91 84510 99371 (Call / WhatsApp) · 2026-09-18
India’s utility-scale and C&I solar market in 2026 is no longer deciding only between Tier-1 suppliers and lowest landed module price. The real decision is technology selection under Indian operating conditions, ALMM-linked procurement constraints, evolving warranty structures, and lender scrutiny on performance assumptions. For developers, C&I offtakers, EPC contractors and financiers, module selection now affects not just capex but generation certainty, degradation trajectory, O&M strategy, spare philosophy and claims enforceability.
This matters because module pricing has narrowed across leading cell technologies, while differences in field performance can materially change delivered kWh over 25 years. In hot Indian sites, a seemingly small delta in temperature coefficient, low-light behaviour, bifacial response or first-year degradation may swing project IRR more than a headline price gap of a few paise per watt.
For Indian buyers, the 2026 question is not “which module is cheapest?” but “which module technology is most bankable and buildable for this site, tariff and financing structure?”
Why module technology selection has become a board-level decision in 2026
Three structural shifts have changed module procurement in India.
First, ALMM and domestic manufacturing policy have reshaped the supplier pool. Buyers cannot assume unrestricted access to every global SKU, and availability can differ by watt class, cell format, BOM variant and delivery quarter. A technology that looks attractive in a datasheet may be difficult to secure in bankable volumes with stable lead times.
Second, larger-format wafers, higher current modules and n-type technologies have altered BOS interfaces. String sizing, inverter current compatibility, cable losses, combiner strategy, clamp zones, tracker torque tube compatibility and transport damage risk all need revalidation. Module choice is now an EPC design input, not a late-stage procurement substitute.
Third, lenders and serious C&I buyers are pushing harder on performance assumptions. They want clarity on first-year degradation, annual linear degradation, bifacial gain basis, PAN-file assumptions, warranty backstops, and whether the chosen technology has enough operational history in Indian heat, dust and humidity.
As a result, module selection now cuts across Procurement & vendor management, design engineering, quality control and financing.
The main technologies in India today: where TOPCon and HJT really stand
In 2026, the practical shortlist for most Indian projects is dominated by n-type TOPCon, with HJT appearing in selective cases and legacy p-type PERC largely confined to price-sensitive or inventory-driven opportunities.
TOPCon has become the mainstream choice because it offers a workable balance of efficiency, manufacturing scale, supplier depth and pricing. Typical commercial utility and C&I module efficiencies in the Indian market are often in the roughly 22% to 23.5% range depending on format and BOM. For most buyers, TOPCon now represents the default bankable technology if supply, warranty language and QA are acceptable.
HJT remains attractive on paper and in selected project conditions because of its strong temperature performance, lower degradation claims and high bifacial potential. However, in India it still faces a narrower approved supply base, possible premium pricing and more limited long-term domestic operating references relative to mainstream TOPCon. That does not make HJT unviable; it means the underwriting bar should be higher.
PERC has not vanished, but for serious 2026 utility and institutional C&I procurement it is increasingly difficult to justify unless the commercial discount is meaningful and the use case is very specific. If a project is competing on tariff or seeking long-term yield certainty, many buyers now prefer n-type despite slightly higher upfront cost.
A practical comparison for Indian procurement teams looks like this:
- TOPCon
- - Broadest market availability in 2026
- - Competitive efficiency and pricing
- - Generally stronger adoption comfort for lenders
- - Needs careful review of LeTID, UV durability, PID resistance and actual field degradation evidence
- HJT
- - Strong temperature coefficient and bifacial upside potential
- - Lower process temperatures can support lower degradation claims from suppliers
- - Usually tighter supplier universe and possible cost premium
- - Requires close attention to encapsulation, metallisation, glass-glass construction details and warranty enforcement strength
- PERC
- - Lower cost in some pockets
- - Familiarity across EPC and O&M teams
- - Weaker long-term competitiveness on degradation and efficiency for many new builds
- - May remain relevant where procurement timing or residual stock creates pricing advantage
What Indian project owners should evaluate beyond module wattage
Too many tenders still overweight peak wattage and underrate site-specific delivered energy. A 615 W module is not automatically superior to a 590 W module if current mismatch, thermal behaviour, degradation and bifacial assumptions are weaker.
Key parameters to evaluate in India include:
- Temperature coefficient of Pmax
- - In high-irradiance, high-ambient states such as Rajasthan, गुजरात, Telangana, Andhra Pradesh and parts of Maharashtra, lower thermal losses can translate into measurable annual yield benefit.
- - Even a few basis points matter in sites with long periods of elevated module backsheet or cell temperatures.
- First-year degradation and annual linear degradation
- - Suppliers may quote first-year degradation around 1% and annual degradation around 0.4% for some n-type offerings, versus higher figures for older technologies.
- - These values should not be accepted at face value. Check warranty triggers, test conditions and exclusions.
- Bifaciality factor
- - High bifaciality can improve rear-side contribution, but only where row spacing, ground reflectivity, module height and soiling conditions support it.
- - In many Indian sites, realistic bifacial gain may be materially below aggressive sales claims if albedo treatment and O&M discipline are weak.
- Mechanical loading and dynamic response
- - Large-format modules interact differently with trackers and fixed-tilt structures under wind-induced vibration.
- - Transport microcrack risk, clamp-zone compliance and mounting method should be validated early.
- Electrical characteristics
- - Higher Isc and Imp affect string design, fuse sizing, connector heating risk and inverter MPPT current utilisation.
- - Some pairings create hidden clipping or suboptimal MPPT loading if engineers only look at DC nameplate.
For this reason, module selection should sit inside integrated Solar & hybrid plant EPC decision-making rather than be handled as an isolated commercial package.
ALMM, domestic content realities and supply-chain bankability
In India, technical preference means little if the chosen module cannot be procured on time under prevailing policy conditions. ALMM status, approved manufacturing lines, product traceability and consistency between tested BOM and delivered BOM are now central issues.
Buyers should ask five hard questions before freezing module technology:
- Is the exact manufacturer and manufacturing line listed and compliant for the intended project category?
- Does the supplier have enough domestic capacity to serve the delivery window without frequent BOM substitutions?
- Will the delivered module match the tested design for glass, encapsulant, cell supplier, junction box, connector and frame?
- Are PAN files, flash reports and type-test certificates aligned to the actual supply lot?
- Is there a credible Indian service presence for warranty response and claims support?
This is where many projects lose months. A vendor may offer attractive pricing for a high-efficiency variant, but then seek substitutions in cell format, encapsulant or backsheet/glass configuration after award. Such changes can affect mechanical behaviour, degradation profile and insurability.
For lenders, module bankability in 2026 is no longer just about global brand recognition. It includes India execution capacity, document reliability, local claims process, and whether replacement supply would remain available five to seven years later.
Site-specific technology choice: utility, C&I rooftop and hybrid projects
There is no universal best module. The right answer depends on land, tariff pressure, ambient conditions, structure type and curtailment profile.
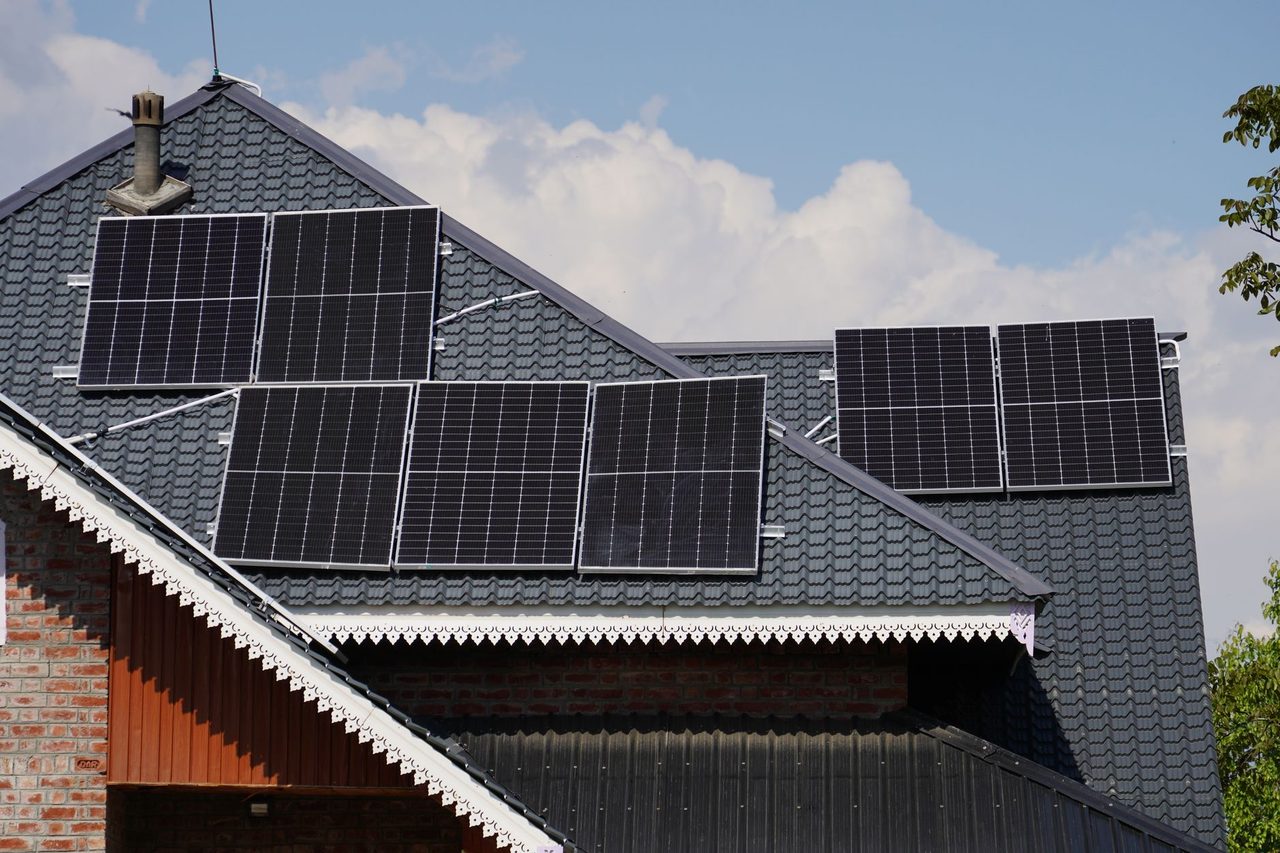
For utility-scale fixed-tilt projects in hot and dry regions, TOPCon is often the practical base case because it combines decent efficiency, strong market availability and acceptable lender comfort. If the tariff is tight and the plant is land-constrained, a high-efficiency n-type module can reduce module count, structure quantity, DC cabling and some installation labour per MW, though not always total project cost.
For premium C&I rooftop projects, module dimensions and weight matter as much as cell efficiency. A very large glass-glass module may look attractive in yield simulations but may complicate rooftop handling, access, maintenance pathways and structural loading. In such cases, a slightly lower wattage but easier-to-install module may create a better execution outcome.
For floating or coastal-adjacent projects, humidity resistance, encapsulant quality, glass-glass design robustness, junction-box sealing and corrosion testing deserve greater weight. Datasheet performance should not overshadow environmental durability.
For solar-plus-storage or hybrid projects, module technology must also align with clipping strategy and dispatch economics. If the project intentionally oversizes DC to improve battery charging windows or flatten export profiles, the generation shape and thermal behaviour of the selected module become more important than STC wattage alone.
EPC and QA issues that can erase technology advantages
A superior module on paper can underperform badly if quality assurance is weak. In 2026, the most common failure mode in Indian projects is not necessarily wrong technology selection; it is inadequate incoming inspection, poor installation discipline and weak traceability.
Priority controls should include:
- Pre-dispatch manufacturing audits for BOM freeze and process control
- EL testing strategy at factory, receipt stage and post-installation sampling
- Verification of flash-test binning consistency and serial traceability
- Transport and unloading SOPs to control hidden microcracks
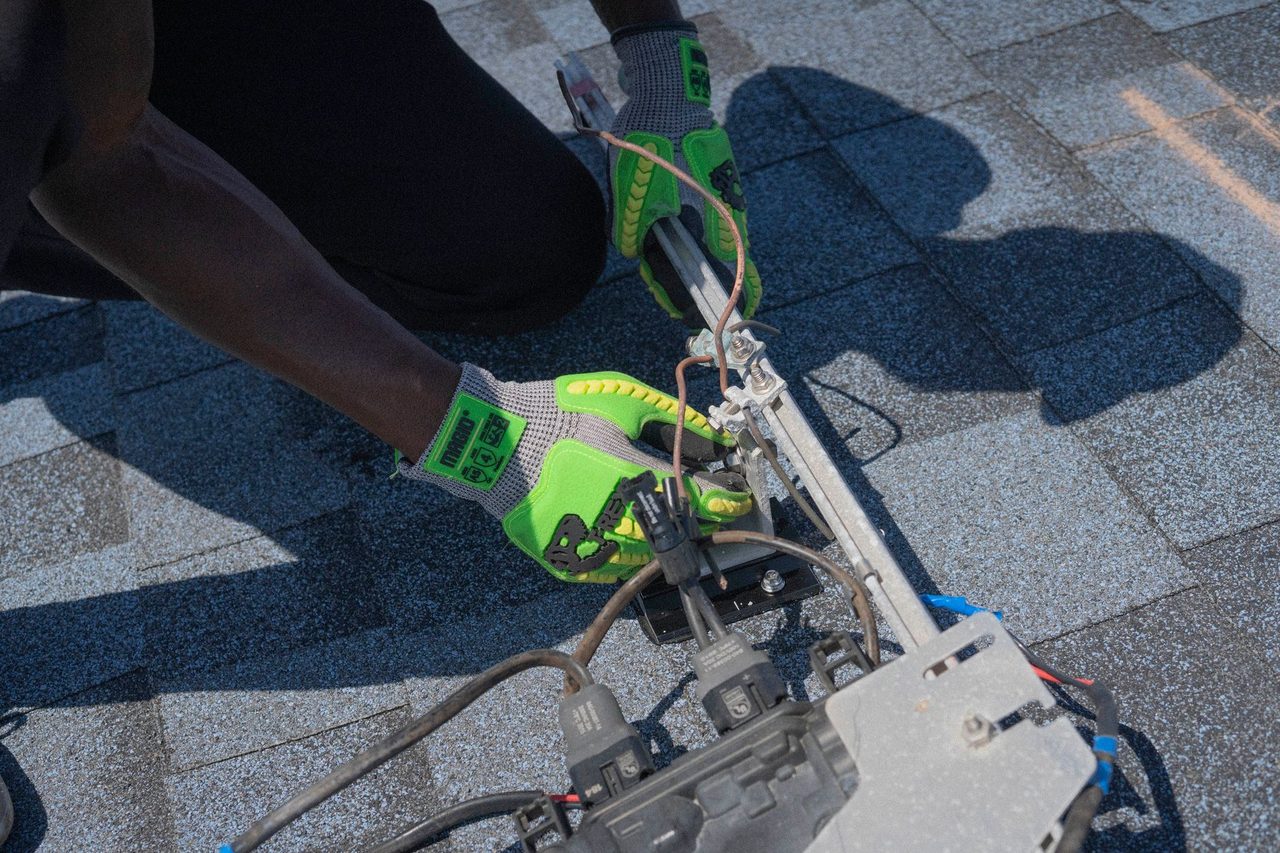
- Clamp-zone compliance and torque control during installation
- Connector compatibility checks; no mixed-brand field improvisation
- Insulation resistance, polarity and string current validation before energisation
For large projects, independent QA/QC & HSE enforcement is often worth far more than negotiating the last 1 or 2 paise/Wp from the supplier. A single quality lapse across thousands of modules can create performance losses, safety events and insurer disputes for years.
Developers should also ensure that acceptance criteria are explicitly written into the supply and EPC contracts. If the contract does not define thresholds for visual defects, power tolerance, EL failure rates, breakage allowance, replacement SLA and field-performance review, later claims become slow and contentious.
A practical decision framework for developers and lenders
For 2026 Indian procurement, a disciplined decision matrix is better than choosing solely on cost per watt. A workable weighting framework can include:
- 25% techno-commercial yield value
- - Temperature behaviour
- - Degradation assumptions
- - Bifacial gain realism
- - PAN-file quality
- 20% supply certainty
- - ALMM alignment
- - Delivery schedule reliability
- - Domestic manufacturing capacity
- - Replacement availability
- 20% bankability and warranty enforceability
- - Financial strength
- - Indian service presence
- - Warranty wording and exclusions
- - Historical claims record
- 20% EPC compatibility
- - Inverter current fit
- - Structural compatibility
- - Installation practicality
- - Logistics risk
- 15% price
- - Landed module cost
- - Packaging and spare policy
- - Commercial terms
This often leads to a different winner than lowest-price procurement. For example, a module that is 3 to 5 paise/Wp cheaper may still lose if it increases schedule risk, forces inverter redesign, raises breakage exposure or weakens debt underwriting assumptions.
In today’s market, realistic technology selection means triangulating module cost against annual specific generation, degradation certainty, replacement feasibility and commissioning timeline. That is exactly where experienced teams across Procurement & vendor management and Testing, commissioning & handover add value.
The 2026 takeaway for Indian solar buyers
TOPCon is currently the mainstream bankable choice for most Indian utility and C&I solar projects, but it should not be adopted lazily. Buyers still need disciplined due diligence on BOM stability, degradation evidence, current compatibility and local support. HJT can be compelling in selected cases, especially where heat performance and long-term yield are heavily valued, but the supplier and bankability review must be tighter.
The bigger message is that module technology selection is now an integrated investment decision. It touches ALMM compliance, EPC design, logistics, QA protocols, lender confidence and long-term asset value. The winning projects in 2026 will not be those that simply buy the highest wattage module or the cheapest quoted price. They will be the projects that choose a technology with the clearest path from factory line to dependable 25-year energy delivery.
If you are evaluating module technology, supplier shortlists, ALMM-linked procurement strategy or field QA requirements for an upcoming project, contact Growthifye’s advisory desk. We support developers, C&I consumers, lenders and utilities with practical diligence across technology selection, EPC execution and commissioning readiness.
Explore Growthifye's related capabilities
This analysis connects directly to our advisory practice: Solar & hybrid plant EPC · BESS system integration · Balance of system & civil works · Procurement & vendor management.
About the author

Chief Executive Officer, Growthifye — With over 23 years in management consulting, Sudarshan has taken businesses from concept to scale — building and scaling new-age digital and energy businesses.
- 23+ years in management consulting
- EY alumnus
- Led large-scale BESS programmes, capital raises and advisory mandates
Want this analysis applied to your project?
Talk to our team